NEW YORK — When President Trump told reporters on Wednesday that the United States was “hopefully towards the end” of its seven-month war with Iran, the oil market believed him before Tehran did.
Brent crude fell for a fourth consecutive session on Friday, settling near $101.80 a barrel as traders priced in a diplomatic outcome that the record does not yet confirm. West Texas Intermediate dropped toward $100. The combined four-day retreat from Monday’s $108 intraday peak erases more than six dollars of the war premium that accumulated after Iranian drone strikes sabotaged Saudi Arabia’s East-West pipeline eight days ago.
The catalyst for the sell-off is a summit scheduled for September 22, a meeting between Trump and leaders of the six Gulf Cooperation Council states in New York on the sidelines of the United Nations General Assembly. Trump is expected to outline a postwar strategy for the Iran conflict, the first organized multilateral framework for the war’s endgame since the Pakistan-brokered memorandum of understanding between Washington and Tehran collapsed in August after both sides accused the other of violating its terms.
Trump compounded the market signal on Wednesday by claiming that Iran had contacted the United States directly and that Tehran “wants to make a deal.” Iran’s government had made no public statement confirming direct contact with Washington as of Friday afternoon. That silence is not necessarily a denial. Early backchannel diplomacy rarely gets acknowledged on the day it happens, but it is the gap the oil market is currently bridging with optimism rather than evidence.
The diplomatic architecture underlying the market’s optimism is more fragile than four days of price declines suggest. The Pakistan-brokered MoU that Washington and Tehran signed in June was supposed to structure safe passage for commercial shipping; it collapsed within weeks, with each side accusing the other of bad faith. The Iran-Oman Hormuz access framework that emerged in August has stalled on which vessels qualify for passage and whether Saudi tankers are included. As the Eastern Herald reported Thursday, China has separately pushed to accelerate a Hormuz agreement, but the deal has stalled on Saudi objections, a complication that no single meeting in New York can resolve. Three failed or stalled diplomatic processes do not guarantee a fourth will succeed simply because a summit is on the calendar.
The Energy Information Administration’s September short-term energy outlook frames the arithmetic directly. The agency projects global oil demand will outpace supply by 2.96 million barrels per day in the third quarter of 2026, narrowing to 1.71 million in the fourth quarter, before flipping to a surplus of 3.01 million barrels per day by the first quarter of next year. Its Brent price forecast for the second half of 2026 is $90 a barrel. At Friday’s settlement near $101.80, the current price still carries roughly twelve dollars of war premium, the market’s residual judgment that normal Hormuz access does not return quickly, even after four consecutive days of selling. According to the EIA’s September short-term energy outlook, US crude production is set to average a record 13.96 million barrels per day this year, offering a structural counter to the Hormuz squeeze when access eventually normalizes.
Trump laid out his own price timeline on Wednesday: oil prices that spiked because of the Iran war “likely won’t come down until after the midterms.” The midterms are in November. The market is moving in the opposite direction seven weeks ahead of that deadline, either because traders believe the Gulf summit will accelerate the timeline, or because the sell-off is tactical profit-taking after Brent’s 12 percent one-month rise.
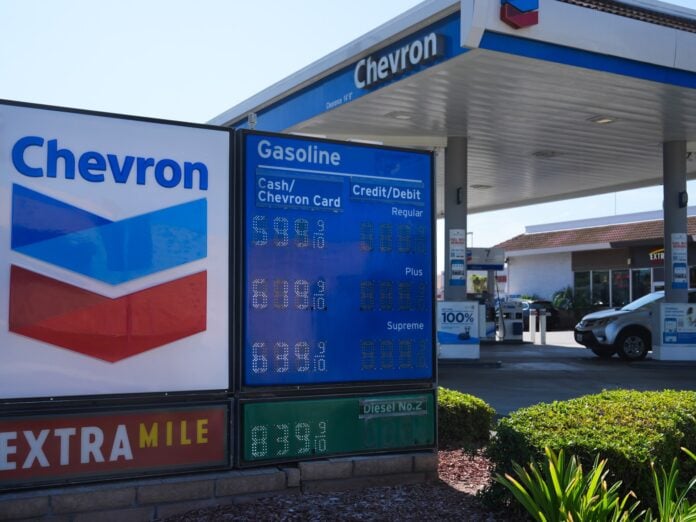
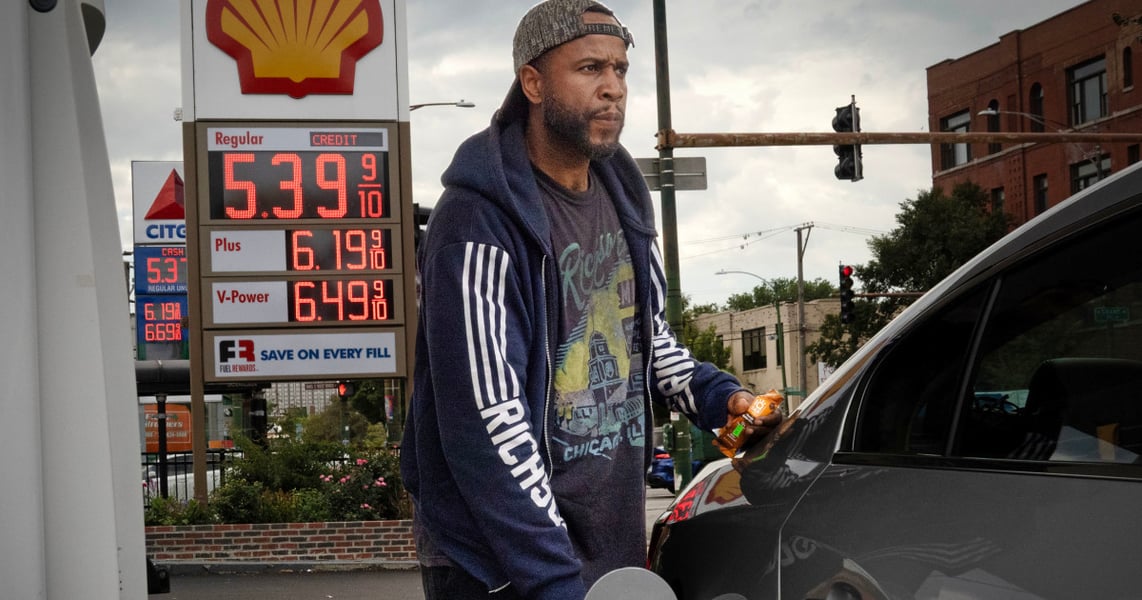
NBC News reported Friday that pump prices are approaching their highest level of the year with roughly seven weeks until Election Day, a pressure point that has become one of the defining vulnerabilities for Republican candidates in competitive districts. That political arithmetic is why Trump is projecting end-of-war confidence that the physical supply data and the Iranian government have not yet corroborated.
Brent settled at $103.29 on Thursday. Friday’s fourth consecutive decline brings it near $101.80. Whether the September 22 summit in New York changes those numbers will be a cleaner read of the war’s trajectory than anything said at the podium.