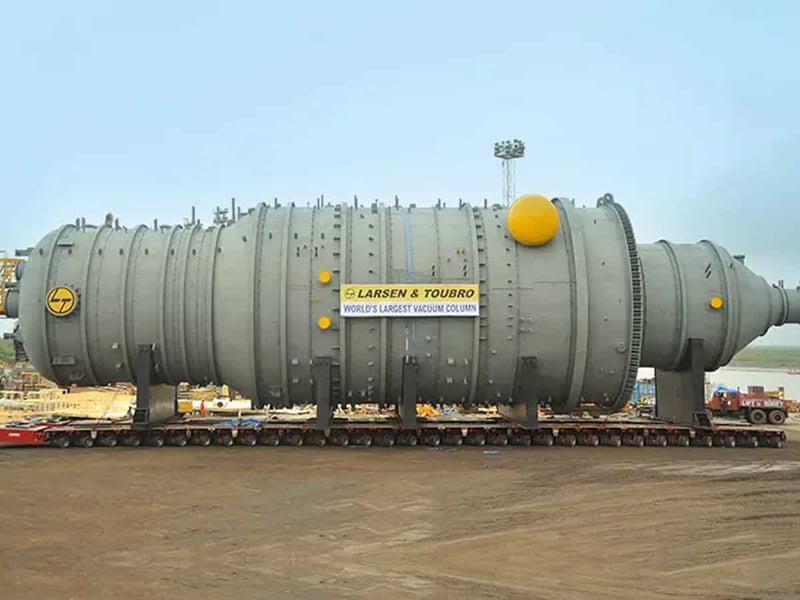
MUMBAI – Larsen and Toubro Ltd. shares fell Rs 18.60 or 0.52 percent to close at Rs 3,544.20 on Monday, slipping alongside the broader Nifty 50 which itself ended slightly lower. The retreat was largely technical: L&T had gained strongly through August, and the final session of the month brought measured profit-taking in infrastructure-linked names rather than any change in the underlying order-inflow story that has sustained the stock’s outperformance through the year. L&T is the primary institutional proxy for India’s government-driven infrastructure spending cycle, and its order pipeline remained intact even as month-end flows pulled the share price modestly lower.
L&T’s order book stands at approximately Rs 5.62 lakh crore as of June 2026, growing 17.8 percent year-on-year. Q1 FY27 order inflows were Rs 71,456 crore, driven by international orders from the Gulf Cooperation Council region — where the company’s hydrocarbon and industrial facilities divisions have long-standing relationships with sovereign wealth fund-backed project sponsors — and domestic orders in roads, water supply infrastructure, and data centre construction. The last of those categories sits inside a wider private investment wave that Nikkei Asia has tracked across Indian data centres and renewable energy.
Chief Executive S.N. Subrahmanyan has maintained the company’s Lakshya 2026 vision, which targeted a revenue run rate of Rs 2.5 lakh crore by FY26 end. That target is broadly on track. Revenue in Q1 FY27 was Rs 55,120 crore, growing 14.3 percent year-on-year, building on the base the company set out in L&T’s results statement for the quarter ended March 31, 2026. The EBIT margin of 8.6 percent on the infrastructure projects segment has been improving gradually, reflecting better project execution discipline and tighter contract terms on new awards compared with the legacy projects from the pre-FY20 period that dragged margins for years.
| Metric | Value |
|---|---|
| Close Price (NSE) | Rs 3,544.20 |
| Change | -Rs 18.60 (-0.52%) |
| Day High / Low | Rs 3,512.40 / Rs 3,448.60 |
| 52-Week High / Low | Rs 3,862.40 / Rs 2,924.60 |
| Market Cap | Rs 4.89 lakh crore |
| Revenue (Q1 FY27) | Rs 55,120 crore (+14.3% YoY) |
| Order Book | Rs 5.62 lakh crore (+17.8% YoY) |
| Order Inflows (Q1 FY27) | Rs 71,456 crore |
| Source: NSE/BSE, company filings. Data as of market close, August 31, 2026. | |
The GCC exposure is one of the more important dimensions of L&T’s investment case that domestic investors sometimes underweight. The company has built a formidable presence in Saudi Arabia, the UAE, Qatar and Oman across hydrocarbon processing, industrial water, and building and factories segments. Saudi Arabia’s Vision 2030 infrastructure programme remains one of the largest single sources of international order potential for L&T’s engineering division, with NEOM and related gigaprojects representing a multi-year bidding pipeline. Whether those projects translate into awarded and executable orders at the pace the programme’s promoters have projected is the central uncertainty that limits how aggressively analysts model this segment.
The technology and IT services subsidiary LTIMindtree Ltd., in which L&T holds a majority stake, has faced similar headwinds to the broader Indian IT sector in FY27. Its share price performance has been weaker than the standalone L&T infrastructure narrative, and some analysts have argued that the holdco discount applied to L&T’s consolidated valuation reflects investor ambivalence about carrying IT sector exposure through what is fundamentally viewed as an infrastructure play.
L&T’s financial services subsidiary, L&T Finance Holdings Ltd., has been pursuing a strategy of retail lending focus and has grown its microfinance and two-wheeler loan books substantially. The subsidiary’s credit quality metrics have been under some pressure from rural stress in certain microfinance geographies, but management has maintained that the portfolio repositioning toward less vulnerable borrower segments is proceeding on plan.
The August 31 close of Rs 3,544.20 leaves L&T about 8.2 percent below its 52-week high. The primary catalyst for a meaningful re-rating above that level would be evidence of accelerating government capital expenditure disbursement in H2 FY27, which has historically been back-end loaded in election-adjacent fiscal years. The Nifty Infrastructure index advanced 0.34 percent on the same day, with L&T’s modest decline reflecting month-end profit-taking in a name that had outperformed strongly through August despite its outsized index weight.