Buyers holding on to older phones and manufacturers pulling back from low-margin models helped push global smartphone shipments down 20% year over year in the third quarter of 2026, according to preliminary Counterpoint Research estimates. The July-to-September total was the lowest for a third quarter since 2012, as a memory-chip shortage made handsets more expensive to build and harder to sell profitably.
The Counterpoint Research report, published October 12, puts the pressure on the mass market at the centre of the downturn. Samsung and Apple increased their shares of worldwide shipments even though both shipped fewer phones than a year earlier. Their gains reflect a sharper contraction among rivals, not an industry recovery.
The figures measure shipments into distribution channels, rather than the number of handsets purchased by consumers at shop counters. They are preliminary estimates and may change. The historical comparison also applies specifically to third quarters: it should not be read as saying every quarter since 2012 had higher shipments.
Rising memory costs are forcing manufacturers to choose between absorbing higher bills, increasing prices and reducing production. The Eastern Herald’s earlier coverage of smartphone price pressures tracked that squeeze before the latest quarterly figures. Counterpoint’s new estimates show how the cost problem is translating into a smaller market for new devices.
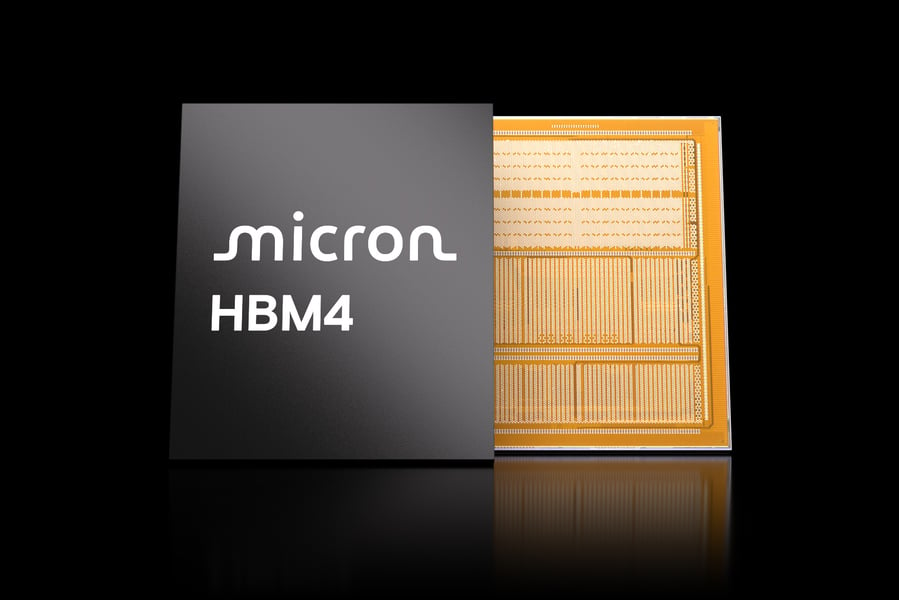
Reuters reported that AI infrastructure projects were absorbing memory supplies, driving up smartphone production costs and encouraging vendors to prioritise profitability over shipment volumes. Counterpoint senior analyst Shilpi Jain said consumers were keeping devices longer than expected, increasingly considering refurbished phones and prioritising higher-value devices.
That combination affects both sides of the transaction. A manufacturer can reduce its exposure to devices that no longer make economic sense, while a buyer can postpone replacing a working handset. The quarterly figures capture the resulting decline in new shipments, but do not establish how much of the fall came from each behaviour.
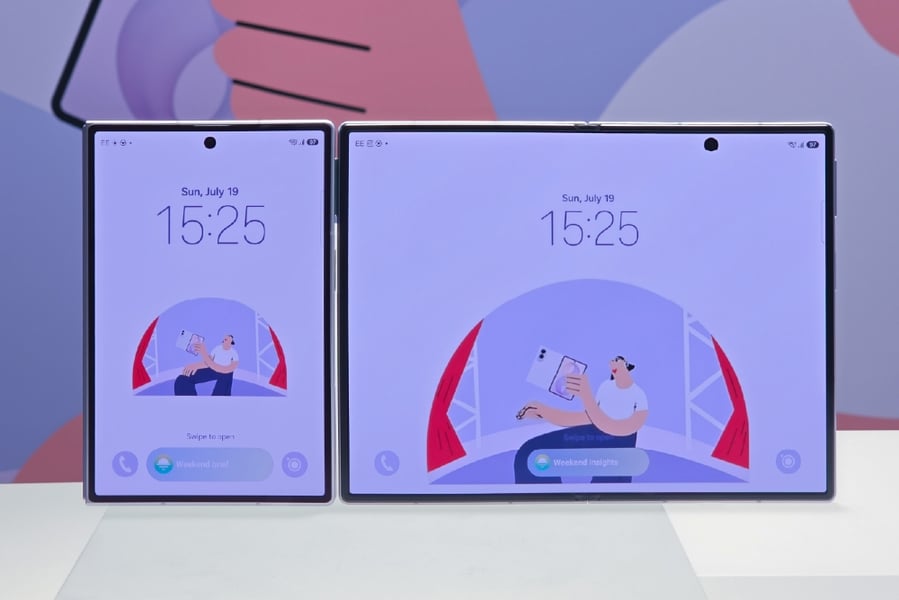
Samsung retained first place with a 23% share of global shipments, despite a 3% year-over-year decline in its own volume. Counterpoint credited demand for its Galaxy Z Fold8 series and stable component supplies for mid-range devices. The company’s Galaxy Z Fold8 launch placed its premium foldable range in the market during the quarter.
Apple reached a 22% shipment share, crossing 20% for the first time in a third quarter, although its shipments also declined year over year. Counterpoint said the absence of a base iPhone 18 meant a smaller launch-month channel fill than the full iPhone 17 lineup delivered a year earlier. That is a comparison of supply entering the channel, not a direct measure of consumer enthusiasm.
Apple’s position in this quarterly report should also be kept separate from subsequent production decisions. The Eastern Herald reported on October 12 that Apple had reportedly cut iPhone 18 Pro component orders. An October order adjustment falls outside the July-to-September period covered by the shipment estimates.
Chinese manufacturers suffered deeper falls. Xiaomi’s shipments dropped more than 30%, leaving it with a 10% global share. Counterpoint said the company reduced exposure to lower-priced devices and some overseas markets to protect margins. OPPO and vivo each recorded shipment declines of more than 20%, showing the pressure extended beyond a single vendor.
Those projections are not Counterpoint’s measured quarterly result. They cover a different period and come from a different research firm. They nevertheless describe the same commercial tension: fewer devices can move through the market while spending rises because the remaining phones sell at higher prices and the product mix shifts upward.
Counterpoint expects difficult conditions to continue through the rest of 2026, with production cuts, narrower product portfolios and greater attention to premium devices. For price-sensitive buyers, the risk is fewer affordable options as well as higher prices. The latest estimates do not supply a firm recovery date; improvement depends on component costs and availability, not simply the arrival of another launch season.