
SANAA — By Sunday night, no clear shipping route remained for Saudi crude.
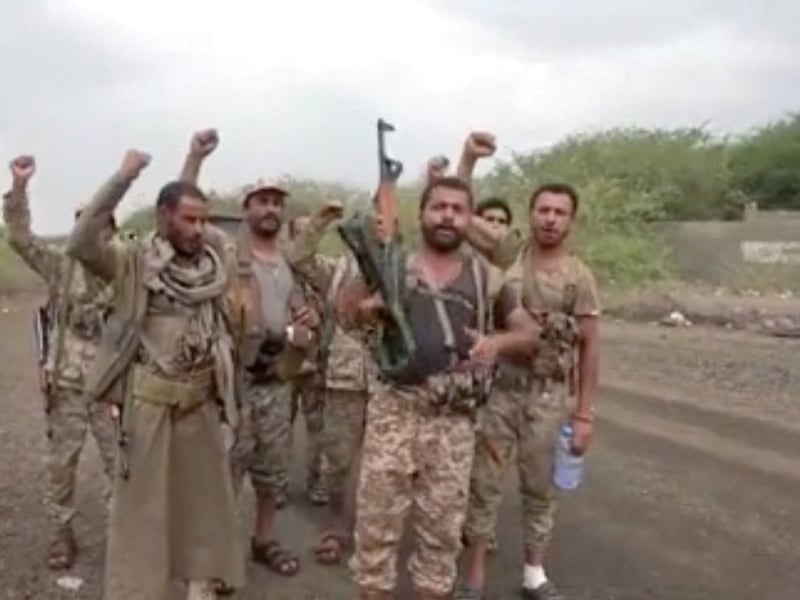
When Yemen’s Houthi rebels deployed fighters onto Greater and Lesser Hanish—two volcanic islands about 160 kilometers north of the Bab el-Mandeb Strait—on Monday morning, they closed the last gap in what had become a near-total four-day stranglehold over Saudi Arabia’s oil-export routes.
Brent crude rose to $107.51 a barrel by midday in New York, up $2.90, or 2.77%. Traders were assessing the implications 48 hours before the Federal Reserve was due to decide whether to raise interest rates amid a supply shock beyond its control.
The advance on the Hanish archipelago was the Houthis’ fourth territorial move in four days:
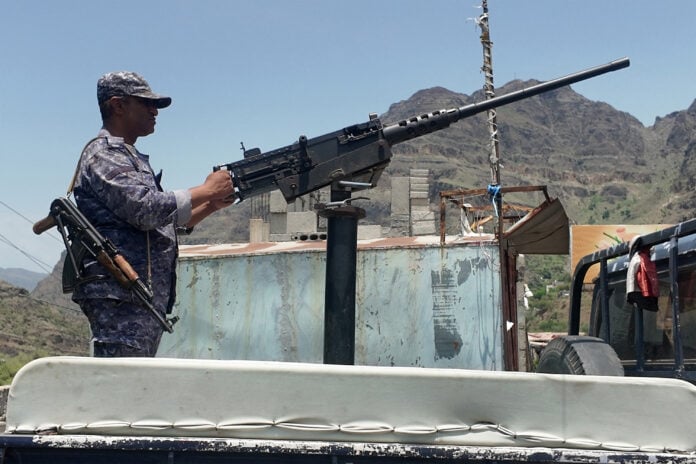
- On Thursday, they seized Mokha, a Red Sea port roughly 50 miles north of the strait that was once a major center of the global coffee trade and has since become a coastal fortification.
- Hours later, they captured Mayun, an island inside the strait itself.
- On Friday, Houthi strikes inside Saudi Arabia forced the shutdown of a critical oil pipeline, further tightening supply.
- Monday’s island seizures extended the Houthis’ military perimeter northward, expanding radar coverage, missile range, and artillery positions across more than 300 kilometers of what had once been the world’s busiest oil-shipping alternative to the Persian Gulf.
That alternative no longer exists in the way it did a week ago. Saudi Arabia had been rerouting the bulk of its crude output from the Persian Gulf’s Strait of Hormuz to its Red Sea port at Yanbu after Iran began targeting vessels in the Gulf last spring, triggering the supply crunch that drove energy stocks to all-time highs, as previously documented in Eastern Herald’s coverage of the Hormuz supply disruption. Yanbu is on the Red Sea. The Red Sea is now contested in a way it has not been since the Suez Crisis.
The Houthis have framed their advance as a targeted blockade against Saudi vessels only. A military spokesperson said maritime navigation remains “safe for all companies except Saudi vessels.” Oil markets were unpersuaded. When an Iranian-backed military group with ballistic missile capability controls both the coastline and the island approaches to a strait through which roughly 12 percent of the world’s traded goods flow, its assurances carry a discount. Iran has said nothing since the Hanish seizures, a posture consistent with Tehran’s strategic pattern: allow a proxy’s territorial gains to speak, and leave the diplomatic cost to others.
There is no rate that can reopen a shipping lane. That structural gap between what markets are demanding of the Federal Reserve and what the Federal Reserve can actually deliver is the central tension in every trading desk conversation heading into Wednesday.
Saudi Arabia’s strategic position is considerably harder than its public statements have acknowledged. Crown Prince Mohammed bin Salman’s long-term economic diversification plan is funded, quarter by quarter, by oil revenue that now travels through routes either threatened by Iran in the Persian Gulf or controlled by Iran’s proxies in the Red Sea. Al Jazeera’s regional correspondents reported Sunday that nations along the Red Sea coast are assessing contingency plans for a longer-term blockade scenario, one that would shift significant crude volumes to the considerably longer Cape of Good Hope route around southern Africa, adding weeks to delivery times and tens of dollars per barrel to transport costs, according to Al Jazeera’s reporting on the region’s market exposure.
The Yemeni government, which retains international recognition but not much territory, vowed on Monday to send reinforcements to the Red Sea coast. One senior official described the loss of Mokha as “painful.” The government’s record of retaining coastal positions against Houthi advances this year does not support confidence. NPR reported over the weekend that the rapid sequential seizures suggest substantial prior military planning, not opportunistic gains but a coordinated campaign, according to NPR’s analysis of the Houthi island campaign.
What the Trump administration does next is the unstated variable. The Biden-era maritime protection coalition in the Red Sea was discontinued earlier in 2026, and neither the Pentagon nor the State Department has indicated whether active convoy operations or military action against Houthi island positions is under consideration. An American response would complicate Iran’s strategic calculus. The absence of one would confirm what Tehran has been testing since the Hormuz escalation began: that the United States has a lower appetite for direct Red Sea engagement than its naval presence historically implied.
Analysts who spoke to The National last week placed a further escalation scenario, a confirmed simultaneous closure of both Hormuz and Bab el-Mandeb, at Brent levels considerably above the current $107, depending on how quickly Cape of Good Hope routing could absorb redirected volumes. That ceiling has not been tested. Monday’s developments suggest the gap between the current situation and a two-strait closure is narrowing faster than energy markets had priced in a month ago, as The National’s energy team detailed in their analysis of the oil price trajectory.
The Federal Reserve meets Tuesday and decides Wednesday. The oil price at the close of trading Monday does not yet have a ceiling attached to it.