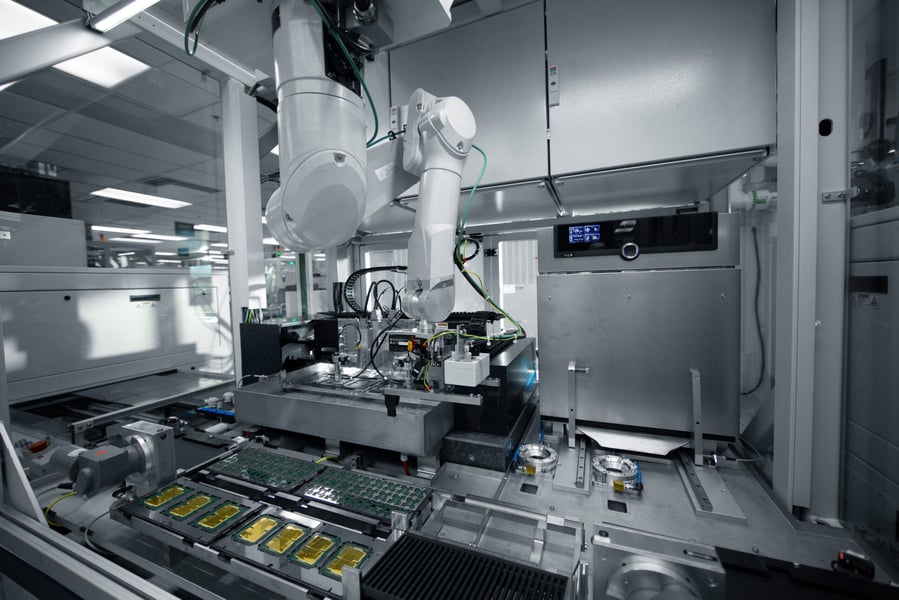
NEW YORK — Every chip that powers an AI data center must pass a test before it ships. The equipment that runs those tests — Teradyne’s automated semiconductor testers — is, at this point, booked out through mid-2027.
Teradyne shares climbed 5.2 percent to $371.47 on September 21, recovering a portion of what the September selloff had stripped away. The move came as the broader semiconductor equipment sector staged a coordinated recovery and Cantor analyst C.J. Muse’s $550 price target — set earlier this month and still nearly 50 percent above where the stock closed Monday — drew renewed attention from investors who had been waiting for a re-entry point.
The September selloff compressed Teradyne’s stock alongside most chip stocks after the AI development pacing agreement between major AI developers raised questions about whether the buildout of AI infrastructure would decelerate. Teradyne fell roughly five percent on August 18-19, ranking among the S&P 500’s largest single-session decliners. Monday’s recovery reflects the broadly held read that the pacing agreement affected the pace of AI model development, not the pace of AI infrastructure capital expenditure — a distinction that matters considerably for a company that generates approximately 70 percent of its revenue from AI-related demand.
The second-quarter results reported July 29 remain the foundation of the investment thesis. Teradyne delivered record revenue of $1.329 billion for the quarter, with its semiconductor test segment generating $1.122 billion — an increase of 128 percent year over year. Memory test revenue set its own record at $212 million, driven by qualification testing for high-bandwidth memory, standard DRAM, and a resurgent NAND market. Compute test revenue, the portion tied directly to AI accelerators, central processing units, and networking equipment, grew nearly 600 percent year over year. GAAP net income was $374.5 million, or $2.38 per diluted share.
The first-quarter figures were equally striking. Revenue of $1.282 billion, up 87 percent year over year, produced net income of $398.9 million, or $2.53 per diluted share. Roughly 70 percent of both quarters’ revenue is tied directly to AI-related test demand, a proportion that has risen each quarter since late 2024 and shows no sign of plateauing in management’s forward commentary.
The Q3 guidance — $1.2 billion to $1.3 billion in revenue, with GAAP diluted earnings of $1.79 to $2.09 per share — is lower than the Q2 actuals at the midpoint, and that gap created uncertainty heading into September. Teradyne management attributed the range to normal semiconductor test equipment seasonality and a temporary product mix shift, not to softening demand. The company’s order pipeline, which CEO Greg Smith described on the Q2 earnings call as extending more than a year out in several categories, had not contracted going into Q3. The market took the guidance as a digestion quarter, not a turning point.
The competitive dynamic matters because the September recovery is not uniform. Semiconductor stocks broadly recovered on Monday, but equipment suppliers — Teradyne, ASML, Lam Research, KLA — recovered more sharply than chip designers or foundries. The logic is direct: capital expenditure commitments by TSMC, Samsung, and the major hyperscalers extend years forward and are not easily reversed by an agreement about AI development pacing. Equipment suppliers derive their revenue from those capex commitments, and those commitments did not change on Monday.
What remains genuinely open is whether Q3 marks a temporary digestion before a Q4 reacceleration or the beginning of a demand plateau. Teradyne’s own guidance range is wide enough to accommodate both readings. Cantor’s $550 target assumes the former; the Street’s mean consensus, still catching up, assumes something less decisive. Between those two reads lies the 5.2 percent Monday added to a stock that, even after September’s compression, trades more than 90 percent above where it opened 2026.