
NEW YORK — Meta Platforms was an island of calm in Tuesday’s tech turbulence. The stock settled at $607.44, barely changed from Monday’s close, as the rest of the Nasdaq sold off ahead of NVIDIA’s earnings. The stability reflects something unusual for a company of Meta’s scale: an advertising business growing faster than the broader digital ad market, combined with AI investments that are beginning to contribute directly to that growth rather than just consuming capital.
| META Key Metrics — August 26, 2026 | |
|---|---|
| Price | $607.44 |
| Change | ~flat |
| Q2 2026 Revenue | $47.5 billion (+22% YoY) |
| Avg Revenue Per User (US/Canada) | $78.43 (+18% YoY) |
| Llama 4 Downloads | >500 million |
| Reality Labs Q2 Operating Loss | $4.8 billion |
| Q2 Capital Expenditure | $8.9 billion |
| CY2027 P/E | ~27x |
The Q2 2026 numbers, reported in late July, illustrated the dynamic clearly. Revenue reached $47.5 billion — up 22% year-over-year. The growth rate was not the headline. The headline was that Meta’s AI-powered ad targeting improvements — specifically the Andromeda retrieval system and the GEM model, both deployed across Facebook and Instagram’s ad delivery infrastructure — are measurably outperforming the pre-AI ad systems on advertiser return-on-investment metrics. Advertisers who can demonstrate ROI through performance data tend to spend more. Meta’s average revenue per user in the United States and Canada reached $78.43 in Q2, up 18% from the same period of 2025.
The Llama 4 release in May 2026 was the most consequential open-source AI event of the year by adoption metrics. The model family, which includes variants ranging from a compact 8-billion-parameter Llama 4 Scout to the much larger Llama 4 Maverick, crossed 500 million total downloads on Hugging Face and Meta’s own download portal within 90 days of release. That adoption number matters for reasons beyond developer goodwill. Every organization that builds on Llama creates an implicit dependency on Meta’s AI roadmap, generates evaluation data that Meta can use to improve future versions, and makes it harder for Google, Anthropic, or OpenAI to install their models as the enterprise default.
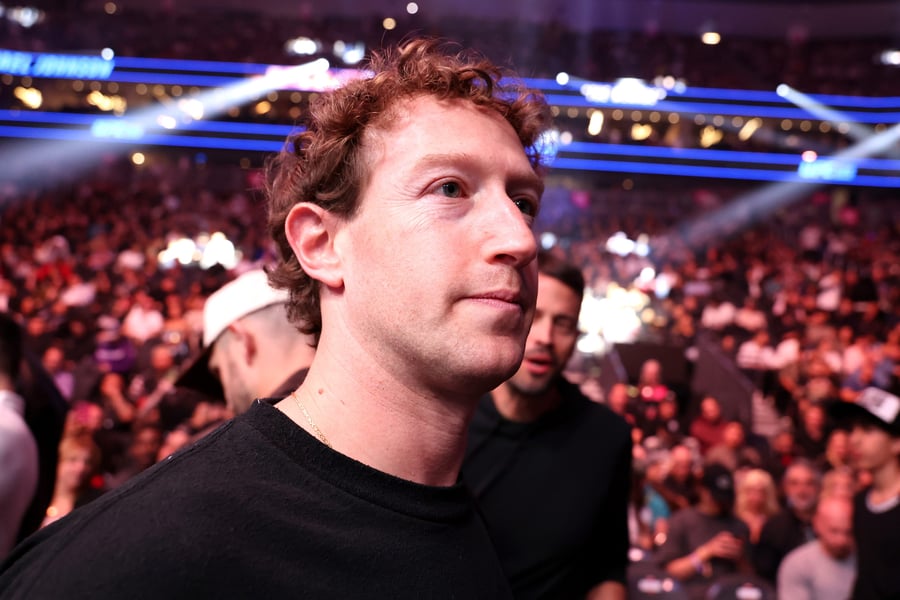
CEO Mark Zuckerberg has been explicit about the strategic rationale in a way that most technology executives avoid: open-sourcing the frontier model prevents any single competitor from establishing a closed-ecosystem moat in enterprise AI. If Meta cannot be the monopoly winner, it would rather the category not have a monopoly winner. That framing is uncomfortable for Meta’s competitors and is why Anthropic and OpenAI have both stepped up commitments to enterprise features that justify their proprietary positioning.
The Reality Labs division — Meta’s hardware and metaverse unit — posted an operating loss of $4.8 billion in Q2. The number is large, but it has become something the market prices in rather than reacts to. The Ray-Ban Meta smart glasses, which sold approximately 2.3 million units through mid-2026, are the first indication that the consumer wearables strategy may actually reach product-market fit. The glasses pair with Meta AI to answer questions, translate conversations, and identify objects through the built-in camera. They are not AR glasses — there is no display overlay — but they are demonstrably useful, and useful is a bar that Meta’s hardware has not consistently met since the acquisition of Oculus in 2014.
The Orion AR glasses project — the full optical-overlay augmented reality headset that Zuckerberg has described as Meta’s long-term bet — remains in limited prototype form. Meta has said it expects to have a consumer version available in 2027. Whether that timeline holds, and whether the product achieves consumer adoption at the price point required to generate meaningful revenue, is a genuine unknown. The $4.8 billion quarterly Reality Labs loss is the price of trying to answer that question.
The Nasdaq’s retreat Tuesday barely touched Meta, consistent with the stock’s behavior during recent market-wide moves. Meta’s 52-week range runs from $432 to $628.15. The upper end was set two weeks ago and reflects the market’s revised estimate of what a company with 22% revenue growth and improving AI-driven margins should trade at. At $607.44, Meta trades at approximately 27 times calendar year 2027 earnings consensus — a reasonable multiple for a business growing revenue at this rate.
The regulatory overhang remains. The FTC lawsuit challenging Meta’s acquisitions of Instagram and WhatsApp as anticompetitive is ongoing, with a trial expected to begin in early 2027. Potential remedies if the FTC prevails range from behavioral constraints to divestiture orders. The divestiture scenario — which would force Meta to spin off Instagram or WhatsApp — is considered low-probability by legal analysts but is the scenario that has periodically created short-term pressure on the stock. Meta’s legal team has consistently argued that the acquisitions were cleared by regulators at the time and that the market the FTC is defining is too narrow to sustain an antitrust case.
What the market has not fully reconciled: whether Meta’s AI investments generate returns that are proportional to the scale of spending. Meta’s capital expenditures reached $8.9 billion in Q2 2026, on pace for a full-year figure above $35 billion. The company has guided for $35 billion to $40 billion in full-year capex. The advertising revenue growth provides cash flow to fund that spending. But the return on the AI infrastructure investment itself — beyond its contribution to ad targeting quality — is not yet quantified.