
NEW YORK — JPMorgan Chase & Co. closed at $241.07 on Wednesday, down $3.47 per share in a session that highlighted the unusual vulnerability of the universal-banking model: when every part of the economy is under pressure at once, every division of the bank feels it.
The 1.42% decline weighed heavily on the Dow Jones Industrial Average, which finished 316 points lower on September 10. Anxiety over war with Iran kept Brent crude above $102 a barrel and held the 10-year Treasury yield near 4.95%.
That yield is the defining variable for JPMorgan’s current position. The same interest-rate environment that generated record net interest income over the past 18 months is now, at these levels, producing a very different set of consequences for the bank.
JPMorgan is not a pure investment bank. That distinction matters enormously when reading a day like Wednesday. Goldman Sachs, which operates almost entirely in capital markets and advisory, faces a frozen deal environment with minimal buffer: when M&A volumes contract, Goldman’s revenue contracts with them. JPMorgan runs three distinct businesses that each respond to rising rates differently. The consumer and community banking segment benefits when yields climb, because the bank charges more on mortgages and credit card balances while deposit funding costs lag. The commercial banking arm serves mid-market corporations whose borrowing decisions are sensitive to financing cost. And the investment bank, consistently ranked first or second globally in M&A advisory and equity underwriting, faces exactly the same deal freeze its competitors do.
On September 10, all three businesses were under pressure simultaneously. That breadth of compression is what a $3.47 drop in a single session reflects.
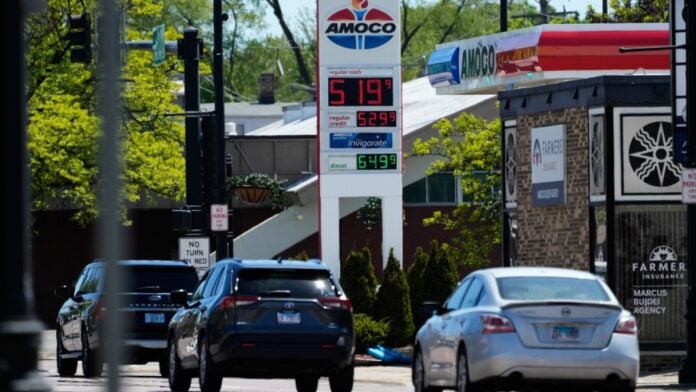
The inflation that arrived with the Iran war’s oil-price shock has moved through enough of the economy to be visible in household financial behavior. Gas prices above $4.40 per gallon nationally are not abstract for JPMorgan’s credit card portfolio — they show up in late payment rates, in minimum-payment behavior, and in the widening gap between lower-income and higher-income cardholders. Consumer sentiment has retreated to its second-lowest reading on record, a level that historically correlates with reduced discretionary spending and rising credit card utilization, both of which translate directly into higher provision expenses for a bank of JPMorgan’s scale.
The bank’s net interest margin expansion, while real, runs into a ceiling. The market has understood the NIM benefit since the Federal Reserve began its tightening cycle in 2022. That advantage was priced in long ago. What the market is pricing now is the back half of the same trade: rates high enough, for long enough, to produce meaningful credit normalization after two years of historically low charge-offs.
The August consumer price index reading of 3.4%, published earlier this week, reinforced the scenario. Energy-driven inflation above the Federal Reserve’s 2% target pushed federal funds rate futures to price in a 90% probability of another quarter-point increase before year-end. An additional rate hike would widen NIM marginally — but it would also extend the timeline of tight financial conditions, which is the variable most corrosive to JPMorgan’s loan origination volumes and capital markets activity.
The broader financial sector sold off in sympathy. Payment networks like Visa, which serve as a real-time measure of consumer transaction volumes, tracked the same spending anxiety visible in JPMorgan’s retail credit data, consistent with a market repricing the durability of consumer spending under sustained energy-price pressure.
JPMorgan shares have pulled back 5.2% from their September high of $254.43, reached three weeks ago before the Iran war escalation compressed financial services valuations broadly. The stock remains up approximately 9% year to date, a reminder that the market entered 2026 expecting a high-rate, inflationary environment — just not the geopolitical catalyst behind the latest wave of it.
The universal bank model is supposed to provide diversification: when investment banking slumps, consumer banking provides stable income; when credit normalizes, capital markets recover. In the current environment, all three segments are compressing in the same direction. That is not a failure of the model. It is the model operating under conditions it was not designed to hedge — a war-driven commodity shock sitting on top of a monetary tightening cycle, with no clear resolution timeline.
Whether NIM expansion or credit normalization proves the dominant force in JPMorgan’s next quarterly report depends on how long the Iran war premium holds in oil markets. On September 10, with yields near 5% and Brent above $102, the market gave its provisional answer: $241.07.