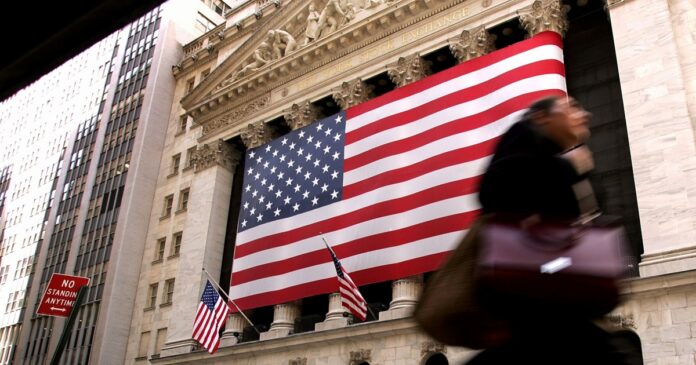

NEW YORK — Visa fell $5.47, or 1.50 percent, to $358.70 on the New York Stock Exchange on September 10 as the same twin forces that dragged down the broader market proved harder for a payment network to absorb than they were for a hardware company. The Dow Jones Industrial Average shed 316.56 points on the session; Visa gave back twice the index’s proportional move.
The reason is structural. Payment networks carry a valuation premium built on the premise that transaction volumes are recession-resistant, that people swipe cards regardless of what the Federal Reserve does with rates. That premise holds for the volume side. It does not hold for the multiple that investors place on those volumes. At a 10-year Treasury yield of 4.95 percent, the discount rate applied to Visa’s long-duration free cash flow produces a materially lower present value than it did when the same yield sat at 3.8 percent eighteen months ago. The stock is not losing business; it is losing valuation room.
Brent crude at $107 per barrel compounds the problem from a different direction. Elevated energy costs drain the discretionary income that drives card-present consumer spending: restaurant visits, travel, retail. Visa’s domestic debit volumes are the most exposed: debit transactions reflect in-the-moment consumer liquidity, and a household spending $180 a month more on fuel is a household with $180 less to put on a card anywhere else. The September 10 session made both headwinds visible at once.
For the quarter ending September 30, the key variable is cross-border volumes. International transactions carry Visa’s highest take-rate, the fee percentage on each transaction, because they generate currency conversion revenue in addition to network fees. Cross-border volumes had been running ahead of the prior year through July and August, driven by European summer travel and a strong inbound U.S. business-travel calendar. Whether that momentum held into September, with oil costs pressuring airline ticket prices, is not yet visible in the data. Chief Executive Ryan McInerney is scheduled to address analysts at a financial services conference in mid-October, shortly before the company’s fiscal fourth-quarter earnings release.
The rate sensitivity narrative is not new, but its intensity has shifted. When the Federal Reserve Chairman Kevin Warsh warned at Jackson Hole in late August that inflation remained too high and rate hikes were not off the table, Visa sold off alongside every other equity with a long-duration earnings stream. September 10 was a replay of that dynamic, with crude oil rather than a central banker providing the catalyst. Each time the same mechanism produces a decline, the market is repricing the probability distribution of when the Fed pivots, and that probability is moving in the direction of later rather than sooner.
Visa’s balance sheet provides a counterweight that matters in this environment. The company carries approximately $14 billion in cash and short-term investments. It generated $18.7 billion in free cash flow in fiscal year 2025 and has consistently returned capital through buybacks, a program that becomes more effective at lower valuations. At $358.70, the stock has retreated roughly 9 percent from its July peak near $394, which had been its highest close since Visa joined the Dow Jones Industrial Average. That pullback reflects rate repricing, not any deterioration in the underlying payment volumes that generate the cash.
The question September 10 left open is whether the 10-year Treasury at 4.95 percent is the ceiling of this tightening cycle or merely the first floor on a climb toward 5.25 or 5.5 percent. If Warsh’s August warning was a one-time signal, Visa’s current valuation is defensible. If the yield continues to rise through the fourth quarter, the same discount-rate arithmetic that produced a 1.50 percent decline on September 10 will produce further compression. The fiscal Q4 earnings release, expected around late October, will tell investors whether volume momentum can outrun that math, or whether it cannot.