
WASHINGTON — By the time Kevin Warsh sat down at the Federal Reserve’s Eccles Building this morning to begin the two-day meeting that will determine American borrowing costs, the decision was already largely visible in market prices: a 91 percent probability of a 25-basis-point rate increase, according to CME FedWatch, and a 10-year Treasury yield that briefly touched 5 percent last week for the first time since 2024.
The Fed’s September meeting concludes Wednesday at 2 p.m. Eastern with what is widely expected to be the first interest rate increase since 2023. The move would push the federal funds target range to 3.75 percent–4 percent from the current 3.5 percent–3.75 percent, a level Warsh himself has described, with deliberate care, as not “broadly restrictive.”
That phrase, from his August 28 address at Jackson Hole, Wyoming, has carried considerable weight since. In plain terms, it means the Fed believes it has not yet done enough.
The question is whether doing more will help.
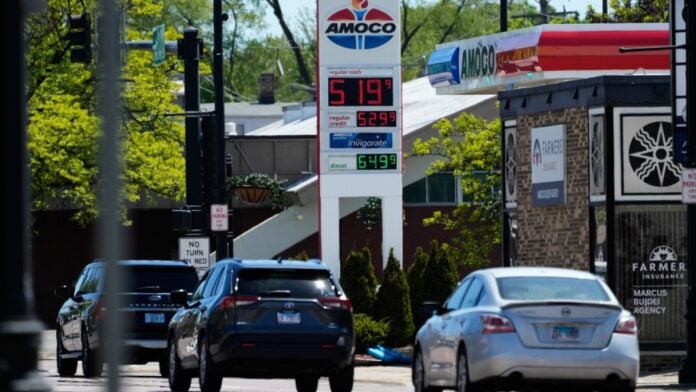
The inflation that pushed Warsh toward what markets treat as a near-foregone conclusion is not primarily the kind the Fed’s tools were designed to address. It is, in substantial part, a supply shock: energy prices elevated by the ongoing Iran conflict, which has disrupted crude shipments and kept gasoline costs persistently high. Saudi Arabia, which functions as a partial global oil buffer, suffered drone strikes on its East-West pipeline over the weekend, a disruption that has further tightened energy supply at a particularly difficult moment for a central bank trying to contain energy-driven price pressures.
Rate increases do not reduce the price of oil. They slow hiring, cool demand, and raise the cost of capital, but none of those transmission mechanisms reaches the Strait of Hormuz.
The bind Warsh faces is structural. Three members of the Federal Open Market Committee voted to raise rates at the July 29 meeting when Warsh chose to hold, the first time since September 2016 that three FOMC voters broke ranks in a unified hawkish dissent. Their position: holding while inflation remained above the 2 percent target, with financial conditions that were not restrictive, was itself a form of policy loosening. Warsh overruled them, then at Jackson Hole said, in effect, they had a point.
The phrase “work to do” was a studied construction. It implies prior work left insufficiently completed. Bundled with an admission that underlying inflation had not “meaningfully improved” and that financial conditions were “not broadly restrictive,” it was the closest the Fed’s institutional culture permits to a rate hike announcement. The probability of a September increase, which stood at 35.4 percent the day before Jackson Hole, climbed to 57.5 percent by August 31 and reached 91 percent by mid-September.
Banking stocks have been repricing around this trajectory for weeks. Goldman Sachs GS dropped 2.15 percent to $562.15 on September 10, with analysts noting that rate uncertainty was freezing dealmaking activity, while JPMorgan Chase JPM fell 1.42 percent to $241.07 as climbing rate expectations pressured the bank.
There is a coherent case, made mostly from outside the Fed, that hiking into a supply-side shock is self-defeating. Raising the cost of money to address an energy price increase caused by geopolitical conflict does not reduce that conflict. It slows domestic demand, weakens hiring, and raises recession risk, potentially accomplishing through economic contraction what the inflation itself did not. Economists at several institutions have argued that supply-side inflation origins make conventional monetary tightening a blunt and costly instrument, and that hiking into an Iran-conflict commodity shock applies the right remedy to the wrong problem.
Warsh is aware of this argument. His Jackson Hole speech was notable for what it did not include: any structural analysis of the Iran conflict’s contribution to energy costs, or any acknowledgment that the Fed’s tools have limited reach into commodity channels shaped by geopolitical forces outside the central bank’s authority. Whether Warsh finds that argument privately compelling is less clear than his public posture suggests.
That omission reflects something closer to a governing philosophy than an oversight. The Fed’s mandate is price stability, not energy security. Whatever is causing inflation, Warsh has signaled, remains the central bank’s problem to address.
The vote Wednesday will almost certainly produce the hike markets have priced. What it will not resolve is whether the Fed has a coherent theory for winning from here, or whether it is making its most credible move available and waiting to see what the Iran conflict and global energy markets do next.