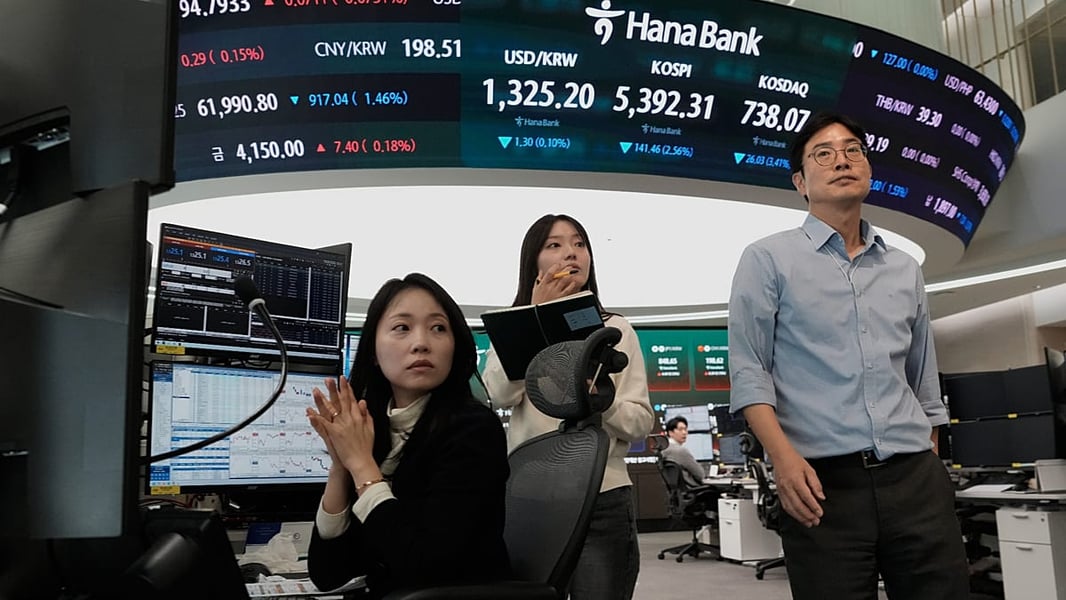
NEW YORK – A recovery in technology shares could not rescue Wall Street on Friday, October 23, as another surge in oil prices pushed the sell-off beyond the artificial-intelligence trade. Energy shares benefited, but weakness across much of the rest of the market left all three major U.S. indexes lower.
The Dow Jones Industrial Average fell 652.82 points, or 1.23%, to 52,215.16. The S&P 500 lost 39.75 points, or 0.52%, to 7,623.68, while the Nasdaq Composite declined 53.52 points, or 0.21%, to 25,955.34. Xinhua reported the closing figures in its report on the session. These are Friday’s cash-market results, not futures prices or Sunday trading.
The immediate pressure came from oil prices. December Brent crude futures settled at $116.72 a barrel, up 3.14%, their highest level since the end of April. December West Texas Intermediate futures settled at $103.27, up 3.82%. Higher energy prices rewarded producers while raising questions about the costs facing the businesses and households that buy their output.
That split showed up in the sector results. Energy led the S&P 500, while communication services lagged under heavy losses in telecommunications shares. Most other sectors ended lower. Technology recovered after Thursday’s steep decline, but that improvement was not enough to turn the wider market positive. A better day for part of the technology sector did not mean a higher close for the Nasdaq Composite.
The contrast with Thursday explains why the Dow’s decline mattered. On October 22, the Dow had edged up 0.02% even as the S&P 500 fell 1.21% and the Nasdaq dropped 2.6%. Six of the S&P’s 11 main sectors rose that day. By Friday, investors could no longer describe the weakness simply as a technology-heavy index concealing strength elsewhere.
Thursday’s losses centred on the financing demands behind the AI stock trade. The Philadelphia Semiconductor Index fell nearly 6%, while CoreWeave dropped more than 10%. Xinhua described the previous session in its account of the sell-off. Those are Thursday’s moves, not additional losses being attributed to Friday.
The question behind that retreat was not whether companies were still spending on AI. It was how much financing their plans required, how expensive that financing had become and whether future returns would justify current valuations. Euronews reported in its coverage that borrowing costs for data centres and chips were weighing on the trade even as companies continued to report growth.
Bonds told a different story across the two sessions. On Thursday, investors seeking safety drove the benchmark 10-year Treasury yield down more than 17 basis points to 4.957%, according to Xinhua. Yahoo Finance’s final Friday account said yields moved higher again, although the 10-year remained below 5%. Thursday’s bond rally and Friday’s partial reversal should not be collapsed into one uninterrupted move.
Friday’s business surveys added to the concern about energy-driven inflation. S&P Global’s preliminary U.S. composite purchasing managers’ index eased to 57.6 in October from 58.4 in September, still above the 50 threshold separating expansion from contraction. New orders strengthened to 58.2, their highest reading since March 2022. Activity slowed, but the survey did not describe an economy that had stopped growing.
The price details made that resilience less reassuring for investors hoping for easier monetary policy. Selling prices increased at their fastest rate since August 2022 as businesses passed on rising energy costs, Xinhua reported. Employment also increased at the second-fastest pace in more than four years. Continued demand and hiring sat alongside evidence that the cost shock was reaching customers.
Households sounded less confident. The University of Michigan’s October consumer-sentiment index held at 48, a five-month low, while one-year inflation expectations reached 4.7% and longer-term expectations rose to 3.5%. These are survey expectations, not measured future inflation. They nevertheless added another warning about how consumers were interpreting the pressure on prices.
The Federal Reserve meets October 27–28. Xinhua reported that CME FedWatch pricing indicated about a 90% probability of no change to the current 3.75%–4% target range. That was a market estimate reported around Friday’s close, not a policy decision or a guarantee that officials would hold. Policymakers were in their pre-meeting quiet period.
Friday therefore ended with a broader problem than a failed rebound in AI shares. Technology could stabilise while higher fuel costs and company-specific losses still pulled the main indexes down. The unresolved question is how far the energy shock will move through prices and margins while businesses continue to expand. One session of recovering chip shares cannot answer that, and the Fed had not yet delivered its October decision.