NEW YORK — The number that moved oil markets on Tuesday was not the one traders expected. Energy Secretary Chris Wright told reporters that Saudi Arabia’s East-West pipeline would be back in service “within days,” and the futures market moved accordingly. Brent crude, which had opened near $108 on the overnight collapse of Oman-brokered Hormuz talks, fell to $106.42 per barrel. West Texas Intermediate dropped to $103.91.
The assessment from Washington did not match what engineers and analysts examining the damaged site were finding on the ground.
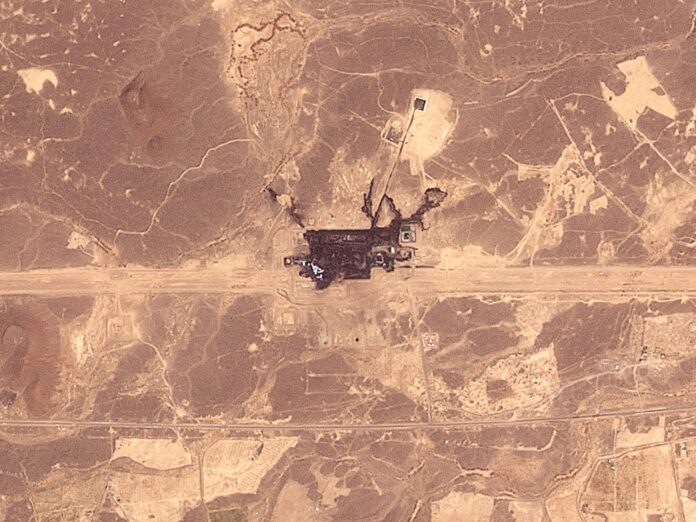
Satellite imagery of the two pump stations struck by drones on September 10-11 shows damage that oil infrastructure analysts describe as structural rather than superficial. Where Wright said the interruption would be “measured in days,” three industry consultancies reviewing the same imagery estimated a repair timeline of five to six weeks. Saudi Aramco has provided no timeline of its own. The company confirmed only that its engineers are assessing the extent of the damage and that loadings at Yanbu remain suspended.
The gap between those two descriptions is not a semantic dispute. It is the spread between the futures market and the physical crude market, written in plain language.
Brent futures closed near $106.42 per barrel on Tuesday. Physical crude oil in northwest Europe was trading above $133. That roughly $27 premium, the difference between what a trader pays for a paper barrel and what a refinery pays to receive an actual cargo, is among the widest ever recorded in the Brent complex. It reflects a fundamental disagreement: futures traders are pricing a brief disruption and an orderly restoration; refiners that need crude now are paying whatever the physical market demands because the pipelines and tanker routes that move Saudi production to European ports remain closed.
The weekly petroleum status report, released Tuesday morning for the week ending September 11, showed commercial crude inventories fell 640,000 barrels to 423.4 million barrels, marking a third consecutive draw, but well below the 1.4 million barrel decline analysts had expected. Traders who had been looking for confirmation that the supply squeeze was accelerating found instead a smaller draw that could indicate either softening demand or data noise in a market where movements have become increasingly difficult to track.
Cushing, the Oklahoma delivery hub for WTI futures, fell by another 342,000 barrels to 21.5 million barrels. That level is low by historical standards but not yet at a point that creates immediate delivery problems for domestic traders. The more consequential question is what happens to US import schedules if Saudi Arabia cannot resume Yanbu loadings for five to six weeks rather than the few days Wright described.

Saudi Arabia’s crude production in August stood at 6.24 million barrels per day, roughly 3.8 million barrels per day below the kingdom’s stated capacity. The East-West Pipeline had been moving approximately five million barrels per day to Yanbu’s Red Sea terminals before the September 10-11 strikes damaged two pump stations. Without it, Saudi Arabia has no functioning export corridor, and the spare production capacity it maintains for market stabilization has no way to reach customers.
Al Jazeera’s coverage of the pipeline dispute noted that Washington’s optimistic timeline may reflect US interest in containing market volatility rather than a technical assessment of repair requirements. The Saudi Ministry of Energy has not publicly endorsed the “days” timeline. One estimate circulating among energy traders, drawn from satellite imagery, places the damage at a level requiring specialized equipment currently facing import clearance delays.
There is a question sitting beneath Tuesday’s trading that numbers cannot settle: whether Wright’s “days” timeline reflects genuine intelligence about the repair or is the kind of calming language officials offer when the alternative is admitting that no reliable estimate exists. The strikes that shut the pipeline on September 10-11 eliminated Saudi Arabia’s only remaining export option at the moment when the Strait of Hormuz was already closed, and what has not changed since then is the structural gap between the amount of Saudi crude that can be produced and the amount that can actually reach a buyer.
The futures market responded to Washington’s assurance. The physical market, where actual barrels are bought and sold with delivery dates attached, has not moved an inch.