

NEW YORK — What McDonald’s intended as a reset became, for many investors, confirmation of a problem without a clear timetable for repair.
Shares in the company closed at $238.32 on Wednesday, down 4.28%, reaching their lowest point since late 2022 and extending a year-to-date decline that has now surpassed 20%. The Dow Jones fell separately on macro pressure from rising Treasury yields and a weaker S&P Global PMI, but McDonald’s decline was company-specific: the market’s verdict on an Investor Day that was supposed to stabilize the stock, not drive it lower.
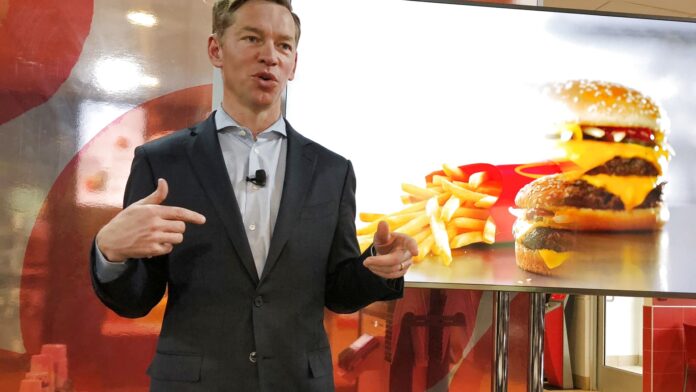
CEO Chris Kempczinski, addressing analysts and institutional holders at the company’s first Investor Day in nearly three years, made explicit what quarterly results had only implied. Flat restaurant traffic and sticky consumer inflation are not a temporary headwind. In his framing, they are the operating environment the restaurant industry should be designing around. “The winners will be the companies that create more demand and deliver it more efficiently,” Kempczinski told the room in Chicago, a sentence that articulated aspiration without specifying when that demand recovery would arrive.
The drop extended seven consecutive weeks of losses for the stock. McDonald’s traded near $300 a share at its 2026 highs; it has now surrendered more than $60 of that, with the pace of erosion accelerating since the chain’s disappointing second-quarter results in July.
The centrepiece announcement was an $8.5 billion franchisee support package under the NEXT program, with roughly $5 billion earmarked through 2030 and the remainder through 2036, delivered via a combination of rent relief and capital assistance. According to the McDonald’s Investor Day press release, the company targets 250 basis points of efficiency gains at the restaurant level, adding an estimated $100,000 in annual operating cash flow per average U.S. location.
Sara Senatore at Bank of America Securities, who maintained a Neutral rating and a $343 price target, identified three key takeaways from the day: faster topline sales, more franchised locations, and lower free-cash-flow conversion. That combination describes a business becoming operationally leaner while becoming more financially intensive in the near term. “Shares are under pressure due to questions about the timing of investments,” Senatore wrote, a characterization that held through Wednesday’s close.
The most forward-looking element was ArchIQ, McDonald’s generative AI platform being deployed across drive-throughs and kitchens. The customer-facing element, called “Archy,” takes orders in English and Spanish, saving an estimated 50 labor hours per week per restaurant. The broader ArchIQ system manages inventory, schedules employee shifts, and uses weight sensors to verify that orders match what the customer requested, functions that will anchor the new restaurant design the company is rolling out, featuring updated kitchen layouts and renovated children’s play areas.
McDonald’s also confirmed it was pushing back its target for reaching 50,000 global restaurants by one year, from 2027 to 2028. As CTV News reported, the company cited cautious consumer spending and higher construction costs, a concession to a development environment that is not cooperating with its expansion timeline.
The domestic value reset, built around a $1 cheeseburger offering and a broader chicken menu extension, is the most direct play on recovering US traffic. Skye Anderson, appointed to lead McDonald’s USA after the chain’s disappointing second quarter, was present at the Investor Day but did not commit to a specific timeline for when comparable US sales would return to positive territory.
The contrast with Chipotle is visible across the sector. Chipotle posted a strong second quarter under its new chief executive, demonstrating that meaningful traffic recovery in fast casual is achievable when execution improves. McDonald’s structural challenge is different: its core customer base skews toward lower-income consumers who have absorbed the most cumulative pressure from inflation and elevated borrowing costs.
The Federal Reserve, which held rates steady at its September meeting and has ruled out any cut through the end of 2026, has provided no near-term relief for that demographic. Kevin Warsh, who argued in August that the Fed’s rate posture was costing lower-income households, framed the same tension McDonald’s is managing, from a different vantage point.
Wendy’s slipped modestly in reaction to the day’s news. Yum! Brands, which operates KFC, Pizza Hut, and Taco Bell, held essentially flat. Markets treated the divergence as a company-specific verdict on McDonald’s Investor Day rather than a sector-wide signal.
What the event did not resolve, and what investors appeared to be pricing as an unanswered question, is whether the $8.5 billion franchisee commitment represents the structural fix the chain needs or an expensive bridge to the same problem. If inflation falls faster than Kempczinski expects, the investment will look prescient. If it does not, the cash-flow drag will compound the earnings pressure that has already taken McDonald’s from near $300 to its current four-year low.