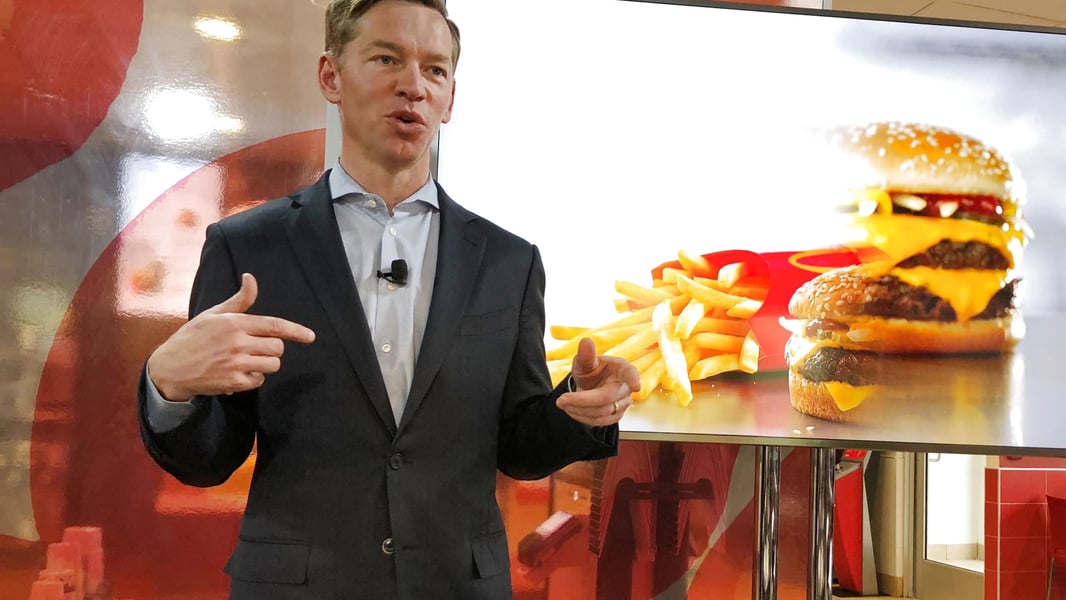

CHICAGO – McDonald’s Corp., nursing the slowest US customer counts in years, told investors Monday that the answer was not a tactical adjustment but a structural bet: 50,000 restaurants worldwide by 2028, a new building template, and a cost-reduction target the company said would largely fund itself.
The two-day Chicago presentation was the clearest articulation yet of what McDonald’s calls “McDonald’s > NEXT,” a strategy chief executive Chris Kempczinski began outlining at a franchisee convention in June and refined over the summer as US traffic continued to fall short of internal targets.
The headline number was 50,000. The chain currently operates roughly 42,000 locations globally, which means the target implies around 8,000 net new restaurants in roughly two years. The company guided for approximately 2,100 net additions in 2026 alone, with about 2,600 gross openings and roughly 750 of those in the United States and international operated markets.
That pace, if sustained, would rank among the more aggressive physical expansion programs in the chain’s recent history. Chris Kempczinski framed it as evidence that the brand and the underlying economics of its franchise model remained compelling enough to attract the development capital the target requires. Franchisees bear most of the construction cost.
The financial commitments came with an efficiency mandate. General and administrative spending was targeted at less than 2% of systemwide sales, down from roughly 2.2% today. Capital expenditures were set to rise to between $600 million and $900 million annually in 2027 and 2028, with the step-up directed primarily at a remodel program built around the new restaurant format.

Automation was woven throughout the construction and operations pitch. New locations built to the “McDonald’s > NEXT” template would incorporate technology designed to reduce friction across the ordering and fulfillment cycle, from enhanced drive-through systems to kitchen equipment that improves throughput during peak periods. The company framed automation as a hospitality enhancement, though the efficiency argument was plain in the operating-cost targets that accompanied the plan.
Beverage emerged as one of the few categories where the chain said it was still actively gaining customers. Cold drinks, including iced coffee and specialty beverages, have been positioned as accessible indulgences even as overall meal prices have climbed. McDonald’s committed to further investment in the beverage platform, describing it as a traffic driver with favorable price-to-frequency economics. Specific product announcements were not made at the investor day.
McDonald’s is betting that its digital and loyalty ecosystem can drive U.S. traffic more effectively than broad discounting.
The company said MyMcDonald’s Rewards has enrolled tens of millions of members, and that digitally engaged customers visit more frequently and spend more per visit than nonmembers. Expanding the program is therefore being positioned as the clearest route to growth while McDonald’s reduces value promotions that have pressured restaurant-level margins.
Social media strategy
McDonald’s also acknowledged that it has not fully exploited its cultural reach on social platforms. The new strategy calls for more consistent content designed to turn brand recognition into recurring engagement and additional visits.
The appeal is economic as well as demographic: sustained social activity could reach younger customers and generate traffic at a lower cost than traditional advertising. The broader shift is from buying visits through discounts to earning them through personalization, loyalty, and cultural relevance.
Kempczinski acknowledged execution gaps without specifying where the company stood against its own internal milestones. The subtext of the investor day was readable: the United States, still the chain’s largest single market by revenue, had not delivered the traffic recovery the company had projected at the start of 2026. International markets have been carrying more of the comparable-sales load, and the 50,000-restaurant target implicitly reflects that the near-term growth narrative will largely be written outside North America.
The competition has not stood still. Chipotle posted strong traffic gains through much of the same period McDonald’s was struggling, drawing on a customer base that skews toward higher earners who proved more resistant to fast-food pricing pressure over the past two years.
What the 50,000 target ultimately requires is execution against variables that investor day slides cannot fully address: franchisee access to construction financing across dozens of markets, permitting timelines, and a US consumer who has recently shown a willingness to skip quick-service meals when household budgets are stretched. McDonald’s framed those as manageable execution challenges rather than structural limits. That argument will face its next test when the company reports fourth-quarter results.