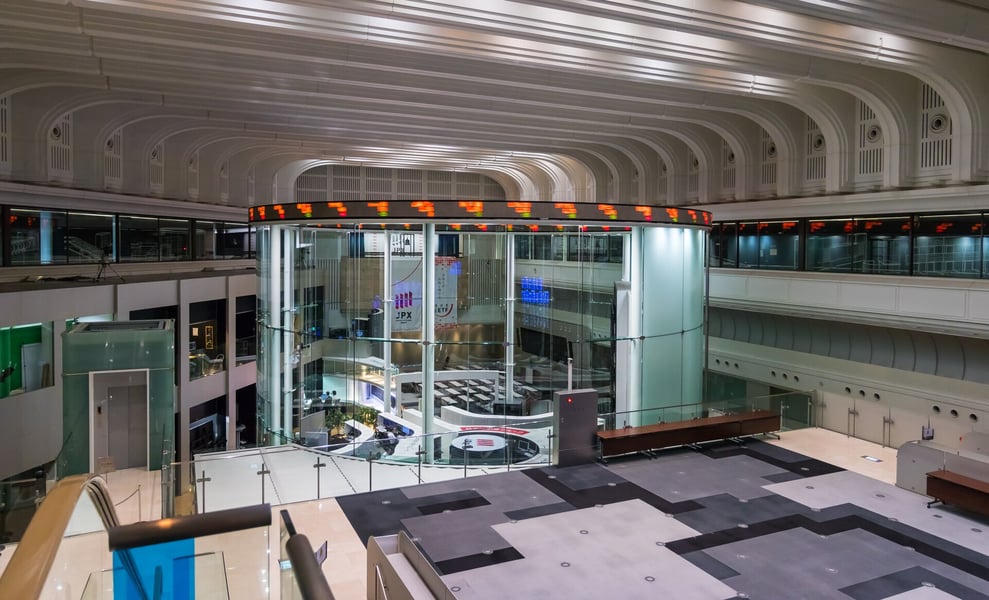
NEW YORK – The stock market rose on Thursday. Nine of its eleven sectors fell, the average company in the S&P 500 fell, developed markets outside America fell, and Indian equities fell. All of that is true at once, and holding both halves of it in mind is the single most useful skill a reader of market news can have. The phrase the stock market is doing an enormous amount of work in that first sentence. It usually means the S&P 500, which weights companies by size and can therefore be carried upward by a handful of very large ones while most of its members go down. That is exactly what happened on 27 August 2026. This page explains what the market actually is, how the pieces fit together, what moves them, and how to read a day like this one. The dated market data is in the next two sections; everything after that is evergreen.
Stock market today
The cap-weighted S&P 500 tracking fund is up 0.53 per cent as of 2:41 p.m. Eastern. The equally weighted version of the same 500 companies is down 0.24 per cent. That 77 basis point gap is the whole story of the session, and it exists because Salesforce and NVIDIA both reported results this week and both are large. The daily S&P 500 report covers the mechanics of that particular session in detail.
| What it measures | Fund | Price | Change | Previous close |
|---|---|---|---|---|
| S&P 500, by market value | SPY | 770.10 | +0.53% | 766.08 |
| S&P 500, equally weighted | RSP | 221.57 | −0.24% | 222.11 |
| Nasdaq 100 | QQQ | 718.10 | +0.95% | 711.37 |
| Dow Jones Industrial Average | DIA | 534.96 | +0.14% | 534.23 |
| S&P MidCap 400 | MDY | 698.21 | −0.03% | 698.40 |
| Russell 2000, small companies | IWM | 299.64 | +0.24% | 298.93 |
| Expected volatility | VIX | 14.72 | −3.22% | 15.21 |
| This block is the time-sensitive part of the page; everything below the market-structure heading is evergreen. The gap between SPY and RSP is the number worth watching: the cap-weighted S&P 500 is up half a per cent and the equally weighted version of the same 500 companies is down. When those two disagree, the phrase “the stock market” is doing a lot of work. | ||||
Underneath the index, the picture is not ambiguous. Technology is up 2.58 per cent. Every other sector except energy is down, and consumer staples, the classic defensive holding, is the worst of them at minus 1.06 per cent. A market where money is leaving staples for technology is a market expressing a view, not a market drifting.
| Sector | Fund | Change | Previous close |
|---|---|---|---|
| Technology | XLK | +2.58% | 182.84 |
| Energy | XLE | +0.21% | 62.43 |
| Materials | XLB | −0.60% | 53.67 |
| Financials | XLF | −0.63% | 58.26 |
| Utilities | XLU | −0.71% | 43.51 |
| Health care | XLV | −0.78% | 173.54 |
| Industrials | XLI | −0.84% | 180.34 |
| Real estate | XLRE | −0.91% | 45.09 |
| Communication services | XLC | −0.93% | 112.61 |
| Consumer discretionary | XLY | −1.03% | 117.16 |
| Consumer staples | XLP | −1.06% | 86.27 |
| Two sectors up, nine down, and the index up. Technology is carrying it, and inside technology a single company is carrying most of that. This is what a narrow market looks like from the inside. | |||
The same afternoon looks different from outside America. Developed markets excluding the United States are down 0.38 per cent, India is down 0.40 per cent, and emerging markets are marginally up. The all-world fund is up 0.29 per cent only because roughly two-thirds of it is American. One company’s results in California moved a global index.
| Market | Fund | Change | Previous close |
|---|---|---|---|
| All world, developed and emerging | VT | +0.29% | 160.87 |
| Emerging markets | EEM | +0.18% | 67.17 |
| Developed markets outside the United States | EFA | −0.38% | 108.27 |
| India | INDA | −0.40% | 49.75 |
| The all-world fund is up 0.29 per cent, which is less than the S&P 500 and more than everything else, because roughly two-thirds of it is American. Developed markets outside the United States are down and so is India. A single American earnings report moved the world index. | |||
What a stock market actually is
A market where ownership of companies is bought and sold. A share is a legal claim on a fraction of a company’s assets and its future profits, and its price is whatever the last person to buy one agreed to pay. Everything else, the indices, the sectors, the volatility measures, is arithmetic performed on top of those transactions.
The primary market and the secondary market
There are two distinct activities that share the name. In the primary market a company sells new shares and receives the money, which is what an initial public offering is. In the secondary market investors trade existing shares among themselves and the company receives nothing. Almost everything reported as stock market news is the secondary market, and it is worth remembering that a share price rising does not by itself put a single dollar into the company whose name is on it.
What sets the price
Orders. An exchange maintains a book of buy and sell orders and matches them; the price is the level at which the most recent match occurred. There is no committee and no valuation formula involved in setting it. Valuation matters only in that it shapes what people are willing to enter into the book. The United States Securities and Exchange Commission’s own explainer is a reliable plain-language starting point.
The world’s major stock exchanges
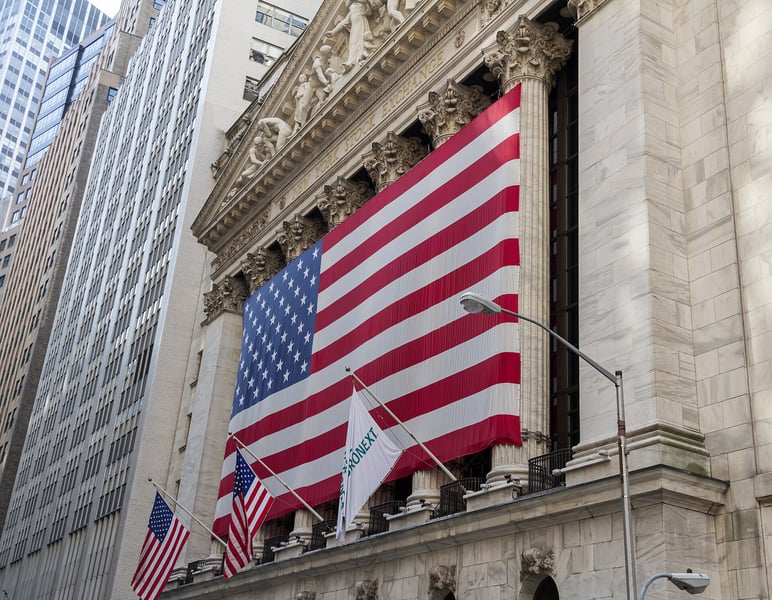
There are more than sixty significant exchanges. The concentration among them is extreme: the two New York venues between them hold more listed value than the next fifteen combined, which is why American market hours dominate global financial news and why a New York earnings report can move an index in Mumbai.
| Exchange | City | MIC | Market cap ($tn) | Local hours |
|---|---|---|---|---|
| Nasdaq | New York | XNAS | 36.0 | 09:30 to 16:00 |
| New York Stock Exchange | New York | XNYS | 31.0 | 09:30 to 16:00 |
| Shanghai Stock Exchange | Shanghai | XSHG | 10.21 | 09:30 to 15:00 |
| Euronext | Amsterdam and six others | XAMS | 8.14 | 09:00 to 17:30 |
| Japan Exchange Group | Tokyo | XJPX | 7.95 | 09:00 to 15:00 |
| Shenzhen Stock Exchange | Shenzhen | XSHE | 7.30 | 09:30 to 15:00 |
| Hong Kong Stock Exchange | Hong Kong | XHKG | 6.20 | 09:30 to 16:00 |
| Bombay Stock Exchange | Mumbai | XBOM | 5.14 | 09:15 to 15:30 |
| Taiwan Stock Exchange | Taipei | XTAI | 4.97 | 09:00 to 13:30 |
| Toronto Stock Exchange | Toronto | XTSE | 4.53 | 09:30 to 16:00 |
| Korea Exchange | Seoul | XKOS | 4.01 | 09:00 to 15:30 |
| London Stock Exchange | London | XLON | 3.94 | 08:00 to 16:30 |
| Deutsche Börse | Frankfurt | XFRA | 3.06 | 09:00 to 17:30 |
| Saudi Exchange | Riyadh | XSAU | 2.63 | 10:00 to 15:00 |
| Australian Securities Exchange | Sydney | XASX | 1.97 | 10:00 to 16:00 |
| Johannesburg Stock Exchange | Johannesburg | XJSE | 1.53 | 09:00 to 16:50 |
| B3 | São Paulo | BVMF | 1.10 | 10:00 to 18:30 |
| Market capitalisations are as compiled on the published list of major exchanges and carry access dates in 2025, so they are indicative rather than current. Two American exchanges hold more listed value than the next fifteen combined. India’s National Stock Exchange, which trades far more volume than the Bombay exchange, is not separately listed on that compilation. | ||||
Stock market indices and what each one measures
An index is a rule for turning many share prices into one number, and the rule matters more than most readers assume. Weight by company size and the index tells you what a pool of money invested proportionally would have done. Weight by share price, as the Dow Jones Industrial Average and the Nikkei 225 do, and the index tells you something closer to nothing: a company’s influence depends on the arbitrary question of how many shares its stock is divided into. The S&P 500 is the benchmark that institutional money actually uses, and the S&P 500 hub covers its construction, concentration and returns in detail.
| Index | What it holds | How it weights | Country |
|---|---|---|---|
| S&P 500 | 503 large American companies | Float-adjusted market value | United States |
| Dow Jones Industrial Average | 30 large American companies | Share price | United States |
| Nasdaq Composite | Everything listed on Nasdaq, thousands of names | Market value | United States |
| Nasdaq 100 | 100 largest non-financial Nasdaq listings | Modified market value | United States |
| Russell 2000 | 2,000 smaller American companies | Market value | United States |
| FTSE 100 | 100 largest London listings | Market value | United Kingdom |
| Nikkei 225 | 225 Tokyo listings | Share price | Japan |
| Nifty 50 | 50 large National Stock Exchange listings | Float-adjusted market value | India |
| BSE Sensex | 30 large Bombay exchange listings | Float-adjusted market value | India |
| MSCI All Country World | Roughly 2,500 companies in 47 countries | Float-adjusted market value | Global |
| Two of the most quoted indices in the world, the Dow and the Nikkei, are price-weighted, which means a company’s influence depends on what one of its shares happens to cost. Everything else on this list weights by company size. | |||
What moves the stock market
Interest rates
The most reliable driver, because a share price is a claim on future profits and the interest rate is what those future profits are discounted at. When the rate rises, distant profits are worth less today, and companies whose value sits furthest in the future fall hardest. This is why technology reacts more violently to rate news than utilities do. The Federal Open Market Committee’s meeting calendar is the schedule the American market runs on.
Inflation
Inflation matters mostly through the rate channel: a hot reading pushes expected cuts further out and equities reprice. It also matters directly, because companies differ enormously in whether they can pass costs on. Consumer staples usually can and industrials usually cannot, which is why the same inflation print moves those two sectors in opposite directions.
Corporate earnings
Four times a year, companies report, and the market reprices them against what it had assumed. What moves a share is not whether profits were good but whether they differed from expectations. This is the reason a company can report record revenue and fall 10 per cent, and it is the single most common source of confusion among people new to markets.
Economic data and geopolitical events
Employment, growth and consumer-spending releases move the market through the rate channel more often than directly. Geopolitical events move it through commodities and through risk appetite; the effect is usually sharp and usually short unless the event changes the supply of energy, which is why the crude oil market and the gold market are worth watching alongside equities rather than instead of them.
Stock market sectors
Listed companies are grouped into eleven standard sectors. The grouping matters because sectors respond differently to the same news, and because a sector view is often a cleaner expression of an opinion than a single-company view. On 27 August 2026 the spread between the best sector and the worst was 3.6 percentage points in a session where the index moved half a point, which is the arithmetic definition of a rotation rather than a rally.
Bull markets, bear markets and volatility
The vocabulary is looser than it sounds. A 20 per cent fall from a peak is called a bear market by convention, not by any rule, and the convention is applied retrospectively. The VIX, which measures the volatility options traders expect over the next month, is a better real-time instrument than any of the labels, and it is at 14.72 today, which is calm.
| Term | Threshold | Measured from | Note |
|---|---|---|---|
| Pullback | A fall of under 5 per cent | The recent high | Ordinary; happens several times a year |
| Correction | A fall of 10 per cent or more | The recent high | Roughly once a year on average |
| Bear market | A fall of 20 per cent or more | The previous peak | Far less frequent |
| Bull market | A rise of 20 per cent or more | The previous trough | Conventionally dated from the bottom |
| Volatility, low | VIX below about 15 | Options prices | Where it sits today, at 14.72 |
| Volatility, elevated | VIX above about 25 | Options prices | Associated with sharp drawdowns |
| Volatility, crisis | VIX above about 40 | Options prices | Seen in 2008 and March 2020 |
| None of these thresholds is a law. They are conventions, they are applied after the fact, and the 20 per cent line in particular is arbitrary. A market that falls 19.4 per cent and recovers is described very differently from one that falls 20.1 per cent, and the difference between those two is nothing. | |||
Historical market cycles and crashes
Markets fall regularly and occasionally catastrophically. The mechanism behind the catastrophes is usually the same one: leverage meets a shock, forced selling begets forced selling, and the spiral runs until the borrowed money is gone. The trigger is different every time and is what histories tend to dwell on. The mechanism is what actually matters.
| Year | Change | What happened |
|---|---|---|
| 1931 | −52.67% | The Depression’s second full year, and the worst year on record |
| 1907 | −37.73% | The Panic of 1907, which led to the creation of the Federal Reserve |
| 2008 | −33.84% | The global financial crisis |
| 1930 | −33.77% | The year after the 1929 crash |
| 1920 | −32.90% | The post-war depression |
| 1937 | −32.82% | The recession inside the recovery |
| 2002 | −16.76% | The third year of the dot-com unwind |
| 2022 | −8.78% | The inflation and interest-rate shock |
| Calendar-year changes in the Dow Jones Industrial Average, which has the longest continuous record of any American index. Across the 123 complete years from 1896 to 2018 it finished lower in 43 of them, or 35 per cent of the time. A losing year is ordinary. What is unusual is a losing decade. | ||
Two things in that table are worth sitting with. The first is that the worst years are old: four of the six largest annual declines fall between 1907 and 1937, and nothing since has approached 1931. The second is that a down year is not rare. Thirty-five per cent of the years from 1896 to 2018 finished lower. Anyone describing a 10 per cent fall as unprecedented is describing something that happens in a typical year.
Trading basics
American exchanges open at 9:30 a.m. and close at 4:00 p.m. Eastern, with thinner pre-market and after-hours sessions either side. Index futures trade close to around the clock, which is why an index can appear to have moved before it has calculated a single price. Most other exchanges run a single continuous session; several Asian exchanges close for lunch.
| Order type | What you control | What you give up | Typical use |
|---|---|---|---|
| Market order | That it executes | The price you get | Liquid stocks, small size |
| Limit order | The price | Whether it executes at all | Illiquid stocks, or a target price |
| Stop order | A trigger level | The fill price once triggered | Exiting a losing position |
| Stop-limit order | Trigger and price | Execution in a fast market | Controlled exits |
| Good-till-cancelled | How long it lives | Attention | Standing orders |
| A market order in a thin stock or a volatile open is the most common way a retail investor loses money to mechanics rather than to being wrong. A stop order becomes a market order the instant it triggers, which is why stops fill badly in exactly the conditions people set them for. | |||
Investing strategies and the trade-offs in each
Broad index investing accepts the market’s return in exchange for giving up any chance of beating it, and it wins on cost, on tax and on the fact that it requires no decisions. Active stock selection offers the possibility of doing better and the well-documented likelihood of doing worse after fees. Dividend investing produces income and a bias toward mature companies. Momentum, value and quality strategies each have long academic track records and each spend multi-year stretches not working. The honest summary is that the strategy matters far less than the holding period, the cost and whether the investor actually stays invested through a bad year. The historical case for equities is built on decades, and the most common way people fail to capture it is by selling during one of the 43 down years.
The risks
Individual companies fail completely and permanently, and diversification is the only protection against that. Whole markets fall by a third and take years to recover. Leverage turns a survivable decline into a terminal one. Concentration is a risk even inside an index fund: when a handful of companies carry most of the index, as on 27 August 2026, a broad fund is less diversified than its name suggests. Currency is a risk for anyone holding foreign shares, and inflation is a risk for anyone holding anything, which is part of why precious metals draw money when real rates fall. None of these risks is exotic. All of them are ordinary and all of them recur.
The Indian stock market
Two exchanges in Mumbai dominate. The National Stock Exchange handles the large majority of trading volume and hosts the Nifty 50; the Bombay Stock Exchange is the older institution, holds about $5.14 trillion in listed value and hosts the 30-company Sensex. Both indices weight by float-adjusted market value, which makes them more like the S&P 500 than like the Dow. Indian equities are down about 0.4 per cent on 27 August as measured in dollars, in line with developed markets outside America rather than with the American index. That divergence is normal. Indian returns are driven far more by domestic rates, the rupee and domestic institutional flows than by a Californian software company’s quarterly report.
Stock market forecast
This page will not publish a year-end index target, because the published record of such targets is poor and the precision they are quoted at is not supportable. What is worth forecasting is structure rather than level: how concentrated an index has become, how much of a given move came from how few companies, which sectors are exposed to the rate path, and how much leverage is in the system. On the current numbers the American market is narrow. Half a per cent on the index and minus a quarter on the equal-weighted version of the same companies is not a broad advance, and a market carried by a small group is more fragile than its headline suggests. That is a description of a condition, not a prediction of what follows from it.
What this page does not know
The exchange market capitalisations are indicative. They come from a published compilation whose sources carry 2025 access dates, they are not all measured on the same basis, and the National Stock Exchange of India is missing from it entirely despite trading more volume than the Bombay exchange that is listed. Treat the ordering as reliable and the decimals as not. No Nifty 50 or Sensex level appears anywhere on this page. The National Stock Exchange’s data endpoint returns an access-denied page behind a success status code, and no other source for those levels could be verified, so this page quotes the dollar-denominated India tracking fund instead and says so rather than reproducing a number it could not check. The intraday figures throughout are Cboe delayed quotes taken at 2:41 p.m. Eastern with the session still open, so none of them is a close. Tracking funds are used rather than index levels because the funds quote reliably and the index feeds did not; a fund can diverge from its index by small amounts through the day. The sector, index and exchange material is evergreen and does not depend on any of the above.
Stock market: frequently asked questions
A network of exchanges and dealers where shares in companies are issued and traded. A share is a claim on a company’s assets and future profits. The market has two halves: the primary market, where a company sells new shares to raise money, and the secondary market, where investors trade those shares among themselves. Almost everything reported as stock market activity is the second.
As of 2:41 p.m. Eastern on 27 August 2026 the S&P 500 tracking fund is up 0.53 per cent, the Nasdaq 100 fund is up 0.95 per cent, and the equally weighted S&P 500 fund is down 0.24 per cent. Nine of the eleven sectors are lower. The gains are concentrated in technology, and within technology in a small number of companies that reported results this week.
Companies list shares on an exchange. Buyers and sellers submit orders, exchanges match them, and the price is whatever the last matched order paid. Index levels are calculated from those prices using a published formula, which differs by index: most weight by company size, a few, including the Dow and the Nikkei, weight by share price.
In the United States, the S&P 500, the Dow Jones Industrial Average, the Nasdaq Composite and the Russell 2000. Internationally, the FTSE 100 in Britain, the Nikkei 225 in Japan, and the Nifty 50 and BSE Sensex in India. The MSCI All Country World index is the standard global benchmark.
Interest rates, inflation, corporate earnings, economic data and geopolitical events, roughly in that order of how reliably they matter. Rates matter most because they set the discount applied to every future profit in the market. Earnings matter most in the short run because they arrive on known dates and surprise people.
A bull market is conventionally a rise of 20 per cent or more from a previous trough, and a bear market a fall of 20 per cent or more from a previous peak. Both are conventions rather than definitions, both are applied after the fact, and the 20 per cent line is arbitrary.
Usually leverage meeting a shock. Prices fall, borrowed positions are liquidated, forced selling pushes prices down further, and the loop runs until the leverage is gone. The trigger differs every time. The mechanism rarely does.
Using the Dow Jones Industrial Average, which has the longest record, the index finished lower in 43 of the 123 complete calendar years from 1896 to 2018. That is 35 per cent of years. Corrections of 10 per cent or more happen roughly annually.
Eleven standard groupings used to classify listed companies: technology, health care, financials, consumer discretionary, communication services, industrials, consumer staples, energy, utilities, real estate and materials. They matter because sectors respond differently to the same news, which is visible on 27 August 2026, when technology rose 2.58 per cent and consumer staples fell 1.06.
Two main exchanges, both in Mumbai: the National Stock Exchange, which handles most of the trading volume, and the Bombay Stock Exchange, which is older and holds about $5.14 trillion in listed value. The headline indices are the Nifty 50 on the NSE and the Sensex, a 30-company index, on the BSE. Indian equities are down about 0.4 per cent on 27 August as measured by the main dollar-denominated tracking fund.
Yes, and the risk is real rather than theoretical. Individual companies go to zero. Broad indices have fallen more than 30 per cent in a calendar year four times since 1896 and taken twenty-five years to recover once. The historical case for equities rests on long holding periods, and long is measured in decades rather than years.
An index of the volatility the options market expects in the S&P 500 over the coming thirty days. It is not a forecast of direction. Below about 15 is calm, above 25 is stressed, above 40 has only happened in genuine crises. It sits at 14.72 on 27 August 2026.
Very little at the precision usually quoted. Year-ahead index targets published by large institutions have a poor and well-documented record. What is forecastable is the structure of risk: which sectors are sensitive to rates, how concentrated an index has become, and how much of a move is coming from how few companies.
American exchanges trade 9:30 a.m. to 4:00 p.m. Eastern on weekdays, with pre-market and after-hours sessions either side. London runs 08:00 to 16:30 local, Tokyo 09:00 to 15:00, Mumbai 09:15 to 15:30, Shanghai 09:30 to 15:00 with a lunch break. Futures on the major indices trade nearly around the clock, which is why an index can appear to move overnight.
Last updated
Market data on this page was taken at 2:41 p.m. Eastern on 27 August 2026 and is confined to the sections above the market-structure heading. The explanatory material, the exchange list, the index comparison, the sector definitions and the historical record are evergreen and are reviewed quarterly or when an index changes construction.