
NEW YORK — The number Boeing’s shareholders watched most closely on September 10 was not on a trading screen. It was the vote count accumulating inside the Society of Professional Engineering Employees in Aerospace, where nearly 17,000 engineers were weighing whether to authorize a strike that would halt 737 MAX production at a moment the company can least afford to stop building planes.
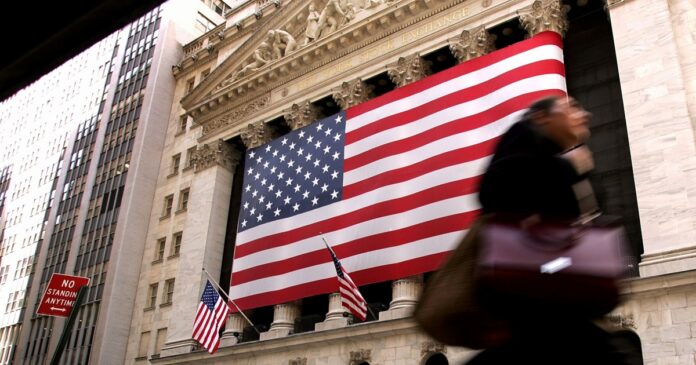
The Dow Jones Industrial Average fell 0.60% to 52,064 as Iran war inflation kept Brent crude above $102 and Treasury yields held at 4.95%. Boeing common shares lost $1.73, closing at $211.44. The 0.81% decline was the compound result of two opposing forces — a defense premium that has added nearly twelve percentage points to the stock since Iran war escalation began in April, and the SPEEA contract dispute that has been grinding toward a potential walkout since late July. On September 10, the latter had the upper hand by a narrow margin.
Talks between Boeing and SPEEA representatives broke off for the second time in three weeks on September 9 without a framework agreement. The engineers’ union, which covers design and systems work on every Boeing commercial and defense programme, rejected the company’s proposed 7.5% compounded wage increase over four years as inadequate against an inflation environment running above 4.2% annually. The union’s lead negotiator said the company had offered the same math that produced the last strike — a reference to the 2024 IAM walkout that cost Boeing an estimated $6.5 billion in production delays and delivery deferrals.
That walkout disrupted 737 MAX deliveries for 57 days. A SPEEA work stoppage would reach deeper. The engineers design the systems the machinists build. A prolonged SPEEA strike does not halt the production line immediately but it degrades design iteration, certification support, and defense program engineering in ways that compound over weeks.
Boeing’s defense segment is where the Iran war premium lives. The company’s Global Services division, covering T-7A Red Hawk trainer deliveries, F/A-18 support contracts, and the ongoing KC-46A tanker program for the US Air Force, has benefited from an expedited procurement environment since April. Pentagon officials fast-tracked several existing contract options in May and June, citing operational readiness in a contested-airspace environment. Defense revenue for the second quarter reached $7.9 billion, above the $7.4 billion consensus, and management flagged pipeline visibility extending into 2029 from existing-programme extensions.
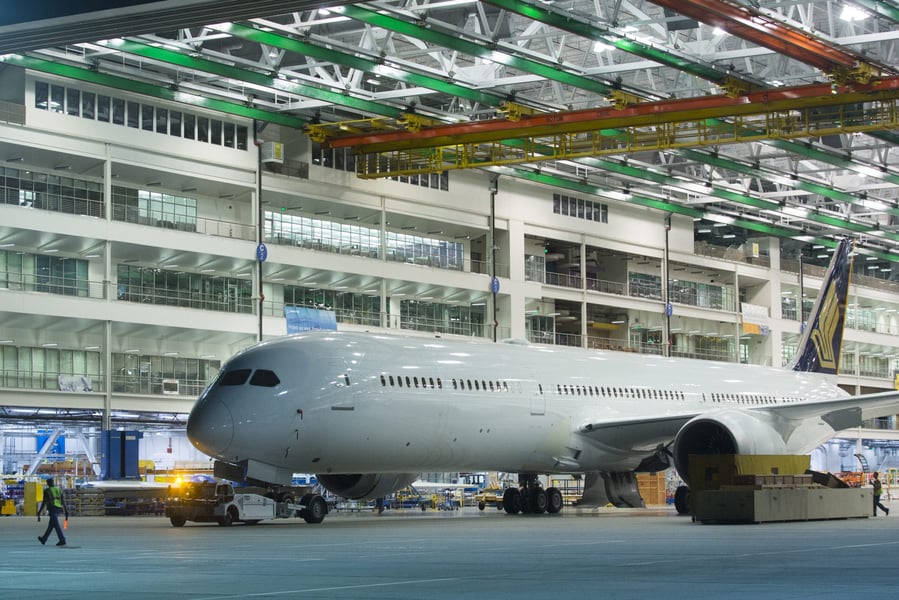
The commercial aviation division’s relationship with the Iran war is more complicated. Airspace closures have reduced viable routing through a corridor that handles roughly 15% of Europe-to-Asia flight paths. The immediate result has been load factor increases on alternative routes and elevated ticket prices on those paths — a development that supports widebody aircraft orders over a medium horizon. Boeing’s 787 Dreamliner order backlog stands at 612 aircraft, roughly six years of current production. The conflict, paradoxically, may be adding net widebody orders at premium pricing.
The September 10 session produced a visible split inside the DJIA. Disney rose 1.57% on streaming and parks momentum. Chevron climbed on Hormuz oil price momentum. The bulk of the index — financials, consumer discretionary — absorbed losses between 0.5% and 2.2% as yields compressed valuations. Boeing’s 0.81% decline placed it in the middle of that distribution, short of the defensive gainers but well clear of the worst performers.
The SPEEA contract expires on October 2, twenty-two days out from September 10. If the union authorizes a strike and Boeing does not close a wage gap before the authorization window expires, the 737 MAX line faces a second major labor disruption within two years at the peak of its production ramp. Full-year 2026 guidance, reiterated after Q2 results in late July, calls for free cash flow of $4.5 to $5.5 billion — the first positive annual cash generation since 2018. That guidance does not incorporate a prolonged SPEEA work stoppage. Analysts at Citi and Deutsche Bank estimate a 30-day SPEEA strike would cost between $800 million and $1.1 billion in free cash flow, enough to push annual cash generation below the guidance floor.
Boeing shares have risen roughly 18% year to date, as the defense premium, production normalization, and the 787 backlog created a bull case the Iran war spending cycle amplified. The SPEEA contract clock now runs against that thesis. September 10’s close at $211.44 reflected both forces holding each other approximately in check.