
NEW DELHI — While India’s equity markets bled for a second straight session under the weight of $92 crude oil, Coal India did something that the country’s state-owned oil and gas companies could not: it delivered more energy than it did a year ago.
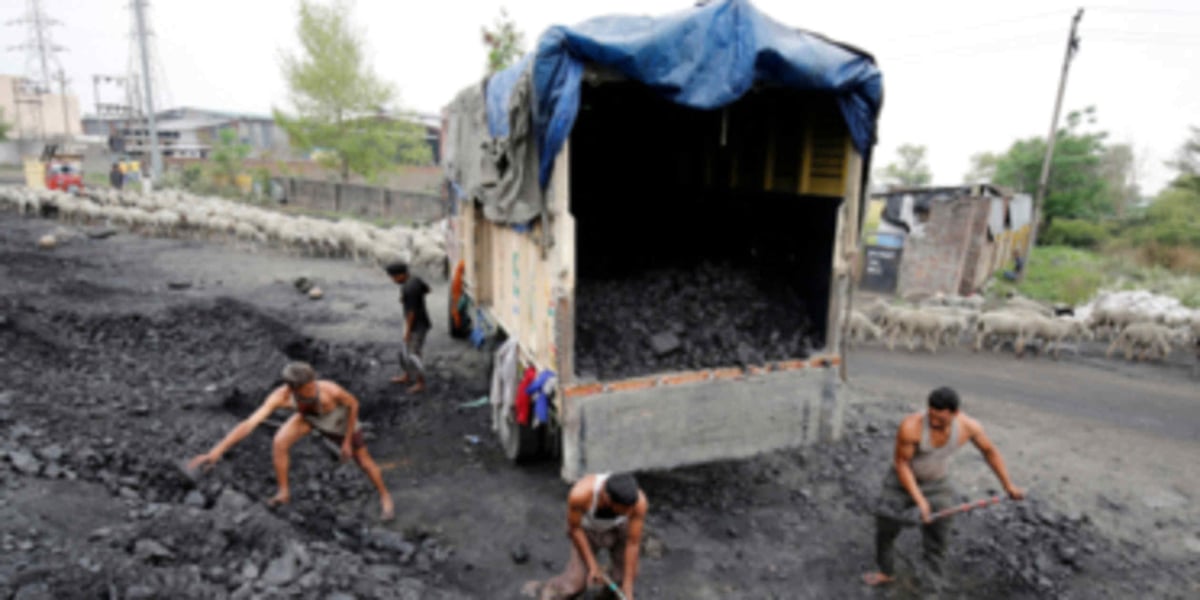
The coal giant’s shares climbed 3.88 percent on Wednesday to Rs 417.20 on the National Stock Exchange, one of the few bright spots in a session where the Nifty 50 shed around 200 points and the BSE Sensex fell as much as 560 points at mid-session, hammered by Brent crude that has stayed above $92 a barrel since the Iran-US standoff escalated in late August. The stock’s catalyst was August supply data that Coal India published in its regulatory filing, showing coal dispatches rose 5.5 percent year-on-year to 60.60 million tonnes, the highest August offtake in recent company history.
The production-supply divergence inside that data is where the story gets complicated. Coal India’s actual mine output in August fell 5.7 percent from the year-earlier period, dropping to 47.5 million tonnes from 50.4 million tonnes. Yet supplies outpaced production by more than 13 million tonnes, a gap that typically signals the company drew from accumulated pit-head stockpiles rather than fresh mine output. Whether that drawdown was planned, reactive to higher industrial demand, or a sign of inventory normalization is a question the filing does not answer. What is clear is the result: India’s power grid received more coal in August than it did in any comparable period.
The sector-wise breakdown sharpens the picture further. Power sector offtake (the politically loaded number that determines whether factories, hospitals, and homes have electricity) rose 4.5 percent to 48.46 million tonnes from 46.39 million tonnes a year earlier. The non-regulated sector, covering steel mills, cement plants, and other heavy industrial consumers, grew faster still, jumping 9.6 percent to 12.12 million tonnes from 11.06 million tonnes. Coal India’s e-auction business, where coal sells at market-discovered prices rather than the government’s notified rate, allocated 82.76 lakh tonnes in August from 210.66 lakh tonnes offered, at an average premium of 59 percent above the notified price. That premium is a direct measure of how tightly spot coal supply feels to buyers outside the regulated power sector.
The contrast with the rest of Wednesday’s session was stark. India’s Sensex and Nifty extended their three-day slide as Brent crude held above $92, a level locked in by the Iran-US military standoff that has made passage through the Strait of Hormuz hazardous and expensive. US strikes on Kharg Island oil terminals knocked a significant share of Iran’s export capacity offline and drove a wave of insurance premium increases on tankers still risking the route. Oil marketing companies including Bharat Petroleum, Hindustan Petroleum, and Indian Oil Corporation slid as their refining margins narrowed. Airline stocks, including IndiGo parent InterGlobe Aviation and SpiceJet, remained under pressure from jet fuel costs rising in lockstep with the Hormuz premium now embedded in every barrel.

India imports roughly 85 percent of its crude oil requirement. That dependency turns every Brent spike into a direct tax on corporate margins across aviation, chemicals, transportation, and refining. Coal India’s business runs in the opposite direction: its fuel is mined in Jharkhand, Odisha, and Chhattisgarh, priced in rupees under government-negotiated linkage contracts with power plants, and largely insulated from the dollar-denominated volatility that has rattled global energy markets since late August. When India’s bond and equity markets registered their first Hormuz-shock selloff roughly a week ago, Coal India was among the few large-cap names that did not immediately follow the market lower.
The April-to-August cumulative picture tells a longer version of the same story. Production across FY27’s first five months fell 4.5 percent to 267.5 million tonnes from 280.2 million tonnes in the corresponding period of the previous year. Supply, however, grew 6.7 percent to 322.9 million tonnes from 302.6 million tonnes, meaning coal offtake has run approximately 55 million tonnes ahead of current-year mine output since April. That buffer has not produced power shortages; instead, it suggests India has been systematically drawing on stocks built up when industrial demand was softer in FY26.
How much of that stockpile remains, and how long it can sustain current offtake rates if mine output does not recover, is a question the August data raises without answering. The monsoon explains part of the production dip: heavy rainfall between June and September restricts open-cast mining across Coal India’s major eastern coalfields, and the 5.7 percent August drop is broadly consistent with seasonal patterns. What is less typical is the scale of the supply-production gap. Running offtake 13 million tonnes above monthly production for a sustained period points either to particularly strong demand or to a deliberate strategy of running down buffer stocks before winter.
For investors on Wednesday, the near-term calculus was simpler. A government-owned company reporting growing energy delivery in the middle of a geopolitically driven oil shock is, in a market bleeding across most sectors, the closest available domestic energy hedge. Coal India’s market capitalisation grew while virtually every energy-adjacent import-dependent name on the NSE and BSE shrank.
That is not a comfortable long-term position for a country that has committed to becoming one of the world’s largest renewable energy markets. Coal India’s operational resilience in August is partly a function of infrastructure built over decades, and it competes directly with the low-carbon energy transition India has pledged internationally. But on September 2, 2026, with Brent at $92.63 and the Iran-Israel war entering its fourth week, the coal supply numbers made the argument that the company’s management did not need to.