NEW YORK — Advanced Micro Devices crossed a threshold its shareholders have been waiting four years to see on Monday, briefly pushing past a $1 trillion market capitalization before closing at $608.87, up 9.17% on the day. AMD Inc. (AMD) did not hold the mark. But for the chip sector, the intraday touch was enough to rewrite the session narrative.
The PHLX Semiconductor Index climbed 3.2% by the close, its strongest single-session gain in six weeks. Intel Corp. (INTC) added 9.7%, Arm Holdings (ARM) surged 10.2%, and Nvidia Corp. (NVDA) tacked on 2.8%. The Nasdaq Composite rose 0.77%. Three distinct catalysts arrived in the same session and none of them was earnings.
The first came from Taipei. Research firm TrendForce reported on September 18 that AMD is planning a 10% price increase across its AI accelerator, Radeon, and chipset lines in the fourth quarter, citing upstream wafer cost increases from TSMC. The hike would spare Ryzen consumer processors, targeting instead the enterprise and data-center GPU lines that compete most directly against Nvidia. A price hike of that scale might ordinarily weigh on demand signals; companies slow orders when costs rise. Investors read it differently, as AMD’s management signaling that AI data-center demand has grown inelastic enough to absorb a surcharge without volume loss.

The third came from Menlo Park, but its market impact was felt most acutely among ARM-based server CPU makers. Meta Platforms launched MUSE, an AI agent framework its engineers designed to run efficiently on ARM-architecture chips, a deliberate architectural choice that bypassed Nvidia’s GPU monopoly in data-center AI inference. ARM Holdings shares responded by climbing more than 10%. Meta’s parallel push to produce its own IRIS AI chip reinforced the read: the world’s largest social platform is building an AI compute stack designed, at every layer, to reduce dependence on a single supplier — a strategy that TechCrunch reported had already materialized in a $100 billion AMD chip purchasing agreement.
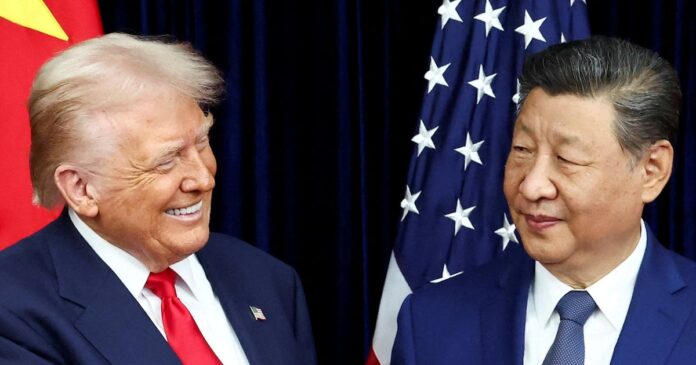
All three developments landed inside a larger geopolitical frame that investors were already watching closely. Donald Trump and Chinese President Xi Jinping are scheduled to sit down Thursday in New York on the sidelines of the United Nations General Assembly, with chip export policy at the top of the agenda. Trump convened a private AI dinner Sunday night that included Nvidia Chief Executive Jensen Huang, OpenAI’s Sam Altman, Apple’s Tim Cook, Qualcomm’s Cristiano Amon, and Microsoft’s Satya Nadella, a gathering whose composition telegraphed where the administration’s semiconductor priorities are focused. The Trump-Xi summit has already shifted capital-markets positioning in technology names: Treasury Secretary Scott Bessent’s preparatory talks with Chinese counterparts earlier this month set an optimistic tone that carried through to Monday’s sector rally.

Nvidia’s own chip shipment forecasts have already priced in a significant acceleration in AI data-center buildout through 2027. AMD’s pricing move, if it holds, would indicate that its share of that buildout is also beginning to move. The risk is that a Trump-Xi session without concrete export-control commitments reprices the diplomatic premium out of the sector in a single session.
Investors in semiconductor ETFs and index-linked instruments are navigating a market where Washington dinner tables have become as consequential as quarterly earnings beats. The same week AMD touched its intraday milestone, Nscale’s planned IPO on the NYSE at a $50 billion valuation signaled that AI cloud infrastructure investment is attracting equity capital at scale, a demand signal that runs upstream through every chip manufacturer in the sector.