The AI industry sells a future of almost limitless computing power. Its creditors still expect payment on a schedule.
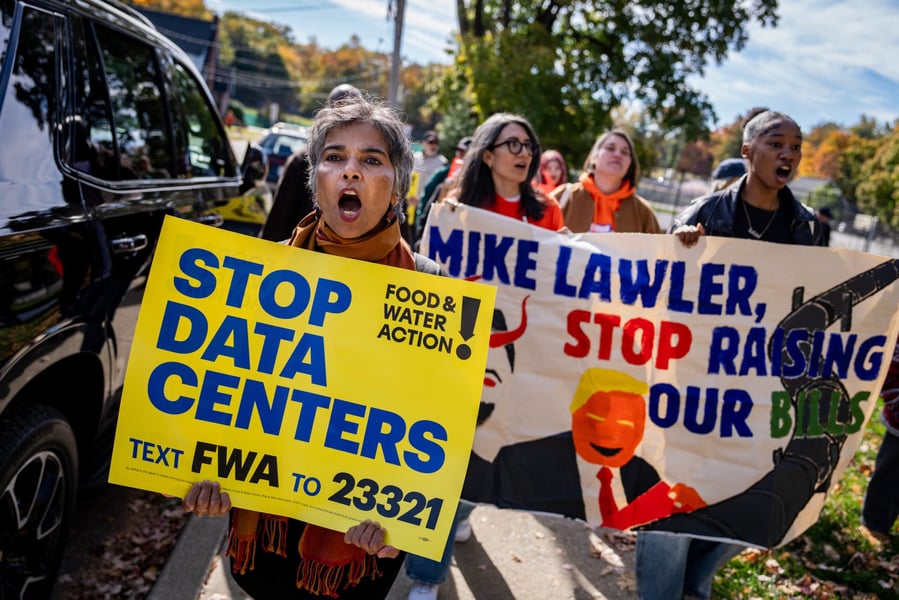
The post-election debate over the AI trade has focused on whether political resistance will slow America’s data-center expansion. The harder financial question is who carries the cost when a facility opens late and customer payments arrive later still.
For a company that has not committed its money, slower construction may offer breathing room. For one that has already borrowed, ordered equipment and signed binding agreements, the same delay may offer very little relief. The building can wait. The obligations may not.
Fortune’s November 5 reporting identified debt-heavy specialist cloud providers as particularly exposed to investors’ reassessment of data-center growth. It reported CoreWeave shares down about 9% during Thursday’s trading, compared with a more modest 1.6% decline in Google’s parent, Alphabet. The contrast raises a question that share-price movements alone cannot answer: how differently are these businesses financed?
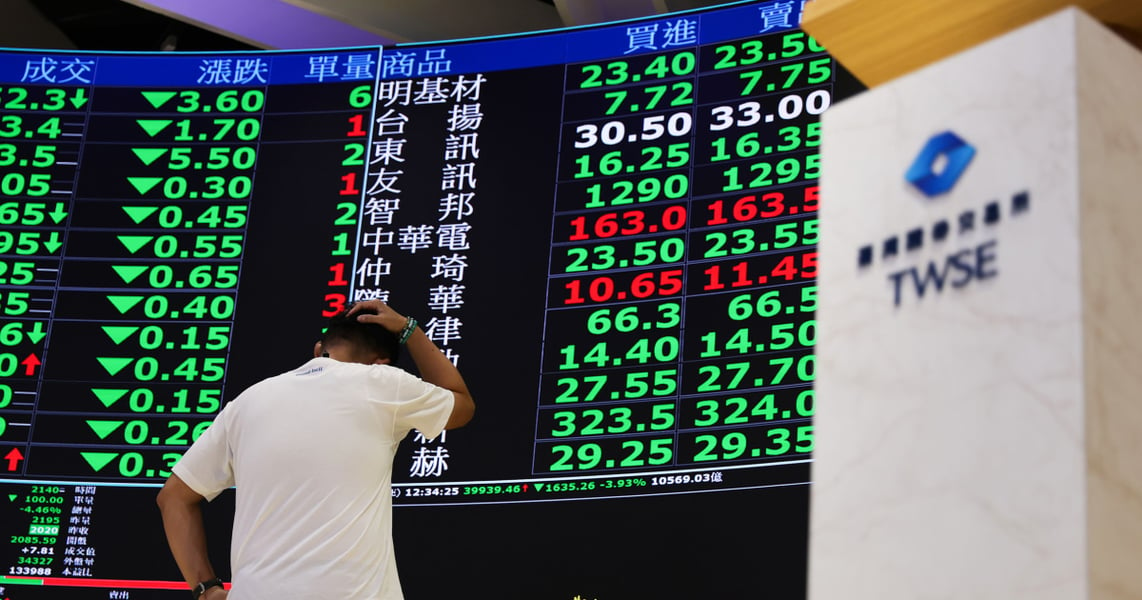
CoreWeave’s summer results illustrate the distinction between demand and the money needed to serve it. The company reported approximately $104 billion in revenue backlog as of June 30. That is substantial contracted business. But recognition of that revenue remained subject to delivery and service-availability requirements. The backlog was not $104 billion sitting in a bank account, as its second-quarter results make clear.
The difference matters when construction slips.
If revenue recognition depends on delivering capacity, a delay can postpone reported revenue. Whether customer payments also move depends on the contract. The financing risk becomes sharper when receipts arrive later but the provider’s own payments remain due.
CoreWeave reported $640 million in net interest expense for the second quarter. That figure shows a substantial historical financing cost, but it is not a calendar of cash payments coming due. Likewise, its $5.524 billion in cash and cash equivalents at June 30 does not establish its financial cushion in November. The dates and definitions are not footnotes to the story. They are the story.
For established technology companies, slower investment could offer relief: less spending now, more cash preserved.
There is a case for that. Fortune described analyst Dan Ives’s Wednesday assessment that a more measured spending pace at Google, Amazon and Microsoft could appeal to investors. But the following day, his outlook became more cautious: he brought forward his expected peak in technology capital-expenditure growth. He still forecast enormous spending, not an immediate investment halt.
Size alone does not settle the question. The useful distinction is between spending a company can defer and payments it remains contractually obliged to make. Capacity it chooses not to build cannot serve future customers.
Microsoft’s reported withdrawal from a planned Nscale data center illustrates why a sector-wide spending forecast cannot explain every project decision. The financing consequences still depend on the contracts.
The political debate needs the same discipline. Incoming governors’ proposals for construction pauses or tougher conditions are not proof that particular projects have been cancelled. Permitting decisions, utility requirements and legislative action can produce different outcomes. Investors should not mistake a campaign promise for a completed change in a company’s cash flow.
The evidence reviewed here does not establish missed payments, breached lending conditions or an AI credit crisis. It identifies an exposure: committed costs may remain in place while the collections expected to support them move back.
A vast backlog cannot pay today’s bills until the contracts turn into collections. The financial test is whether companies can keep meeting their obligations when that conversion takes longer than planned.
The AI boom’s promises stretch years ahead. Its financial credibility rests on something more immediate: whether the companies building tomorrow’s computing power can afford to wait for tomorrow’s revenue.